
Anthropic files for Nasdaq listing: is the ANTH perp a stock substitute?
Anthropic has filed its S-1 with the SEC and wants to trade on the Nasdaq under the ticker ANT. On Hyperliquid the bet on it is already running, across four markets with three different prices.




Which topics should we dive deeper into?
Select what genuinely interests you. Your picks feed directly into our editorial planning.
Crypto news that's actually worth your time.
Weekly. 60 seconds. Carefully curated by our editors: no hype, no promo flood, no spam.
Anthropic filed the prospectus for its stock market listing with the US Securities and Exchange Commission on Monday. Long before the first share changes hands, a bet on it is already running on the trading venue Hyperliquid. Buyers there do not get a share, though. They get an open-ended futures contract on an estimated valuation.
What the prospectus says: Class A, Nasdaq Global Select Market, ticker ANT
Anthropic PBC has been on the SEC register with an S-1 filing since October 26, 2026. The prospectus contains the sentence that matters for the listing: the company has applied to have its Class A shares quoted on the Nasdaq Global Select Market under the ticker ANT. Anthropic is incorporated under the law of the US state of Delaware as a public benefit corporation, that is, a company with a public-good purpose written into its charter alongside the profit motive.
Two figures are still missing from the document, and they are the two that count most. The number of shares on offer appears as a gap in the text. On the price range, the prospectus says only that the issue price per share will fall between two amounts that are not yet named. While those fields stay empty, there is no official price for a bet to orient itself by. You can read the prospectus in the original; it sits publicly in the SEC register.
The prospectus names no timetable. According to an October 26 report by CoinDesk, the company is aiming to price the offering in mid-November; the same report has the Financial Times expecting a valuation of between $1.5 trillion and $1.75 trillion. Those are expectations held by market participants and observers, not figures from the filing itself.
$16.3 billion in revenue, a $693 million operating loss
The prospectus discloses the numbers for the first half of 2026. Revenue came in at $16.286 billion, up from $1.163 billion in the first half of 2025. Total operating expenses ran to $16.979 billion. That leaves an operating loss of $693 million on revenue that has grown more than tenfold in the space of a year.
The annual series before that reads as follows: $41 million of revenue in 2023, $386 million in 2024, $4.585 billion in 2025. The largest expense line is compute and infrastructure, at $8.945 billion in the first half of 2026 alone. For cash and short-term investments, the balance sheet shows a position of $131.651 billion as of June 30, 2026.
The $80.7 billion loss: what sits behind the headline
Many reports on the prospectus carry the figure of $80.7 billion as the loss for the first half. The figure is correct, and it misleads the moment anyone treats it as an operating result. Of that amount, $72.388 billion falls on a single balance sheet line: the change in the fair value of convertible notes, derivative liabilities and so-called SAFEs, agreements on future equity.
The prospectus explains that line itself. It traces mostly to the fair value of the outstanding convertible notes rising because the valuation of the company has risen. There is no cash flow behind it, only a revaluation on the balance sheet. The higher an investor rates the company, the larger this accounting loss turns out to be. A further $8.757 billion sits under other expenses.
The same pattern runs through the earlier years. The fair value change was $1.0 billion in 2023, $5.4 billion in 2024 and $34.3 billion in 2025, against reported net losses of $1.5 billion, $8.3 billion and $42.0 billion. Anyone betting on a falling price with the $80 billion argument is therefore betting against a number that grows along with a rising valuation.
 Compare the biggest perp DEXs by fees
What a pre-IPO perpetual is, and what it does not deliver
A perpetual future, or perp, is a futures contract with no expiry date. It tracks a reference price, and to keep it from drifting away from that price, buyers and sellers pay each other a balancing fee at short intervals, known as the funding rate. A pre-IPO perp tracks the estimated valuation of a company that is not yet listed on an exchange.
Nothing is delivered in the process. You receive no share, no voting right, no dividend and no claim should the company be taken over. You hold a position against other market participants, collateralised with a stablecoin pledge. If the price moves against you and the pledge no longer covers it, the position is closed by force.
Technically these markets run on Hyperliquid as builder markets: an operator sets up its own market and decides the reference price, the maximum leverage and the quotation unit itself. According to Cryptobriefing, one of the Anthropic contracts can also be reached through the MetaMask wallet app, which lowers the barrier for retail investors further.
MiCA or MiFID II: which rules a contract like this falls under
A perpetual on a company valuation is not a crypto asset within the meaning of the EU regulation MiCA. It is a derivative. In the European Union that puts it under the MiFID II rulebook, so the requirements for financial instruments apply instead of the obligations for crypto service providers. We have written up what this classification means for leveraged products in detail in our classification of perpetuals under the CFD rules.
In practice that means the operators of these builder markets hold no German licence, and they do not present themselves as investment firms either. There is no investment advice there, no appropriateness test and no deposit protection. A licensed house in Germany would have to meet every one of those points.
Four markets on the same company, three different prices
How many Anthropic markets exist on Hyperliquid and what they cost had not been compiled anywhere until now. The figures below rest on the publicly viewable market data from Hyperliquid; all 550 perpetual markets across the ten builder marketplaces and the main book were checked, as of Tuesday, 2.40pm German time. Cryptoticker.io gathered this survey itself on October 27, 2026.
Four of those 550 markets quote Anthropic, and they do it in three different units. The market with the ticker io:ANTH stood at 1,893.70 points, 0.22 percent above its level 24 hours earlier, with twelve-times leverage, open positions worth $54.06 million and daily turnover of $19.24 million. The market xyz:ANT was quoted at 115.57, 16.25 percent below the previous day, at ten-times leverage, with $7.41 million of open positions and $15.33 million of daily turnover.
The two remaining markets are all but empty. para:ANTH stood at 115.45 at ten-times leverage, vntl:ANTHROPIC at 1,619.30 at three-times leverage; in both, Tuesday afternoon brought next to no open positions and no turnover at all. Buy into an empty market and you pay whatever the single counterparty asks, and you barely get out again when the pressure comes.
That spread is the real finding. The high quotes follow a convention that several reports describe as one point standing for roughly $1 billion of implied company valuation. The low quotes appear to work in an estimated price per share. Comparing the numbers across two of these markets therefore makes no sense, and none of the four quotes is a share price. The easiest one to mistake is xyz:ANT, because ANT is precisely the ticker Anthropic has applied for to use on the real Nasdaq listing.
 Find a regulated broker for US stocks
Tax: capital gains instead of a one-year holding period
With cryptocurrencies held directly, you know the one-year holding period after which a sale stays tax free. That rule cannot be carried over to futures contracts. As cryptoticker.io set out on October 12, 2026 in its analysis of the taxation of crypto futures and perps, these trades attract the German flat capital gains tax of 25 percent plus the solidarity surcharge, and they do so from the first trade onwards.
Then there is loss offsetting, which follows its own rules for derivatives and cannot be set against other categories of income at will. A provider without a German licence withholds no tax and issues no annual statement. The filing therefore rests entirely with you. Which programmes capture these trades cleanly and produce a statement for the tax office is shown in our comparison of crypto tax tools; for larger positions, a trip to a tax adviser is the cheaper option.
How to check whether a provider is licensed in Germany
BaFin maintains a public company database listing every licence it has granted. For European houses, the supervisory authority ESMA keeps its own register of authorised providers. If you find a name in neither directory, that is not a sign of a gap in the database. It is the answer to your question.
Two further points are settled in a few minutes. If a platform asks for no identity check, it is not working to European anti-money-laundering rules. And if the terms and conditions name a place of jurisdiction outside the European Union, a dispute leaves you with no German court in which to sue for your money.
Twelve-times leverage, funding and liquidation: what the bet costs
Retail investors in Germany face a leverage cap of 2:1 on contracts for difference on crypto assets, together with a forced close once half the collateral has been consumed and protection against losing more than the money paid in. The Anthropic markets measured here offer six times that cap. At twelve-times leverage, an adverse move of a little over eight percent consumes the pledge, and a 16 percent daily move is what one of the four markets delivered on Tuesday.
The running costs, by contrast, are moderate and differ sharply. The funding rates measured work out to a charge of around 1.4 percent a year on a long position in io:ANTH, while xyz:ANT ran at around 0.3 percent a year even slightly in favour of buyers. In para:ANTH the rate stood at around 25 percent a year, which carries little meaning in a market without turnover. These rates are not fixed fees; they shift by the hour with the imbalance between buyers and sellers.
The pledge sits as a stablecoin on the platform, away from any German bank. That leaves you carrying the risk of the stablecoin, the risk of the platform and the risk of the individual market operator setting the reference price, on top of the price risk.
Key dates: price range, subscription and first day of trading
The next documented step is an amendment to the prospectus entering the price range and the number of shares. Only then is an order of magnitude fixed, and only after that does the subscription phase begin. CoinDesk puts the market's expectation at mid-November and, citing the television journalist Liz Claman, November 19 or 20 for the pricing. The company has named no date for the first day of trading.
Until then this holds: every number standing in a pre-IPO market is the opinion of those trading there about a price nobody yet knows. Investors in Germany who want to hold Anthropic shares in a portfolio after the listing need a broker with access to the Nasdaq, and no perp at all.
Anthropic IPO: the price range is still missing from the prospectus
- Wait for the price range. While the share count and the range sit empty in the prospectus, there is no yardstick for a valuation. If you want to gather experience with open-ended futures contracts before then, look at the fees and leverage caps of the providers in the perp DEX comparison.
- Settle your access to the share. For ANT after trading starts you need a portfolio account with a US venue. Which houses offer that and at what cost is shown by the broker comparison.
- Look at the market, not just the price. Leverage, funding rate and open positions belong ahead of every order. Two of the four Anthropic markets were empty on Tuesday, and an empty market costs more than a bad price. Tools that display such metrics market by market are listed in the comparison of analytics platforms.
(As of October 27, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Frequently asked questions about the Anthropic IPO
Transparency note: This article was produced with the assistance of artificial intelligence and reviewed by our editorial team before publication. All figures and claims were checked against the primary sources linked in the text. The feature image was generated with AI.
Related articles
- Hyperliquid Price Explodes 22%: Here Is the Next Target
- SpaceX IPO Today: SPCX Stock Opens Near $152 and Jumps Toward $172 — What Happens Next?
- Ondo launches Private Markets: what a pre-IPO note means for your payout and your tax bill
- How to Buy SpaceX Stock (SPCX): IPO Date, Valuation, and the 3 Best Platforms
- Pump.fun launches perpetual futures with 40x leverage: what to watch now
Which topics should we dive deeper into?
Select what genuinely interests you. Your picks feed directly into our editorial planning.
Crypto news that's actually worth your time.
Weekly. 60 seconds. Carefully curated by our editors: no hype, no promo flood, no spam.

July 9, 2026 4:32 PM
Will the SpaceX Stock Price Crash? What Comes Next After the Post-IPO Slide
SpaceX shares have slid from their debut highs back toward the offer price. Here is what is driving the drop and what could happen next.

October 25, 2026 1:37 AM
NEAR opens cross margin for 50 Hyperliquid perp markets at up to 40 times leverage
NEAR released a cross-margin mode for its Hyperliquid perps on October 22, 2026: more than 50 markets, leverage up to 40 times, collateral at account level instead of per position. The price falls 9.9 percent the same day, and in the backstop procedure cross margin puts the whole account on the line.

October 13, 2026 10:26 AM
Hyperliquid falls 5.9 percent while Bitcoin loses 0.8: $1.66 billion of leverage sits on HYPE
HYPE drops to $82.61 while Bitcoin gives up only 0.8 percent. An own survey of the exchange shows why: $1.66 billion of open leveraged positions stand against $611 million of daily turnover.
August 11, 2026 5:24 PM
Perp DEX Explained: How Funding Rate, Liquidation and Taxes Work on Perpetual Futures
Perpetual contracts run without an expiry date, and in exchange you pay funding for as long as you hold them. This article explains the mechanics behind perp DEX, the liquidation thresholds and the regulatory and tax framework in Germany.
August 6, 2026 1:00 PM
$42 Million in Eight Days: Why ‘Decentralised’ Stopped Protecting Perp DEX Traders
Ostium and AFX were drained inside eight days – both times through keys, not smart contracts. The seven questions you must answer before any deposit.
August 4, 2026 3:53 PM
SpaceX Stock (SPCX): From $211 Record to $104.83 Low in 5 Phases
SPCX trades 44% below its IPO week peak and 12% under the $135 offer price. The chart splits into five clear phases, and earnings land after the close.

May 31, 2026 12:25 PM
HYPE Token Hits $70 All-Time High: 4 Reasons for the Surge
Hyperliquid ($HYPE) hit a $70 all-time high, entering the top 10 cryptos. Here are the regulatory changes and revenue fundamentals driving the pump.
April 19, 2024 11:54 PM
Bitcoin Advocate Michael Saylor Sells MicroStrategy Stocks Amid Price Surge
What lies beneath Michael Saylor's stock sale amidst MicroStrategy's price surge and Bitcoin's upcoming halving event?
June 22, 2026 6:08 PM
SpaceX (SPCX) Crashes 10% as Bond Spree and Lockup Fears Spook Investors — Here's Why
SpaceX shares are sliding hard after a historic Nasdaq debut. We break down what's behind the SPCX pullback, where the stock trades now, and what comes next.
September 18, 2026 10:20 PM
Hyperliquid at a Record High: What Is Behind the HYPE Jump Above $90 and What to Check Before Buying
HYPE, the token of the trading platform Hyperliquid, has set a new all-time high at $92.56. The trigger is a new lending function. What is behind it, what risks the rise brings and what you should check from Germany before buying.
August 13, 2026 8:19 AM
SpaceX Stock Up 40% in 5 Days: SPCX Adds $530 Billion as Musk Bets the Company on AI
SPCX has ripped 40% higher in five sessions, adding roughly $530 billion in market value. Here is what is driving it and what the chart says next.
June 16, 2026 11:16 AM
How to Buy SpaceX Stock (SPCX): Step-by-Step Trading Guide
SpaceX stock (SPCX) jumped to $192 on its second trading day. Here's the price action — and exactly how to trade SPCX step by step.
June 13, 2026 10:33 AM
SpaceX IPO Recap: SPCX Closes +19% in a Record Debut, While Tokenized Stocks Stumble
SPCX jumped 19% to a $2T+ valuation on day one — but the tokenized SpaceX trade split in two, and the difference is the real lesson.
May 14, 2026 3:55 PM
US Stock Market Adds $11 Trillion in 45 Days: Is a Crypto Rotation Imminent?
The US stock market just added $11 trillion in value. Discover why this massive liquidity surge signals a bullish rotation for Bitcoin and altcoins.
June 7, 2025 12:19 PM
Circle Stock Explodes After IPO: What’s Behind USDC's Wild Debut?
Circle, the company behind USDC, just made Wall Street history. After pricing its IPO at $31, the stock soared to over $100. But what’s driving the hype—and is it sustainable?
October 21, 2026 7:15 PM
What is Hyperliquid? Its own blockchain, the HYPE token and access from Germany
Hyperliquid ranks 11th with a market value of $18.12 billion and runs its order book on a layer-1 blockchain of its own. What HyperCore, HyperEVM and the HYPE token do, what trading costs, and what applies to access from Germany.
September 30, 2026 10:13 PM
Robinhood Announces Perp Futures With 10x Leverage for US Customers: “Markets don’t work without traders”
Robinhood plans to offer eligible US customers perpetual futures on eight cryptocurrencies, with up to 10x leverage on Bitcoin and Ethereum. Nothing is tradable yet, and a different leverage cap applies in Europe.
September 15, 2026 4:12 AM
Using Hyperliquid from Germany: What Applies to Your Funds Without a MiCA Licence
Hyperliquid is not entered in any EU register as an authorised crypto-asset service provider, and for perpetual futures a MiCA licence would be the wrong paperwork anyway. Here is what that means in concrete terms for your funds, your keys and your tax return.
June 13, 2026 11:45 AM
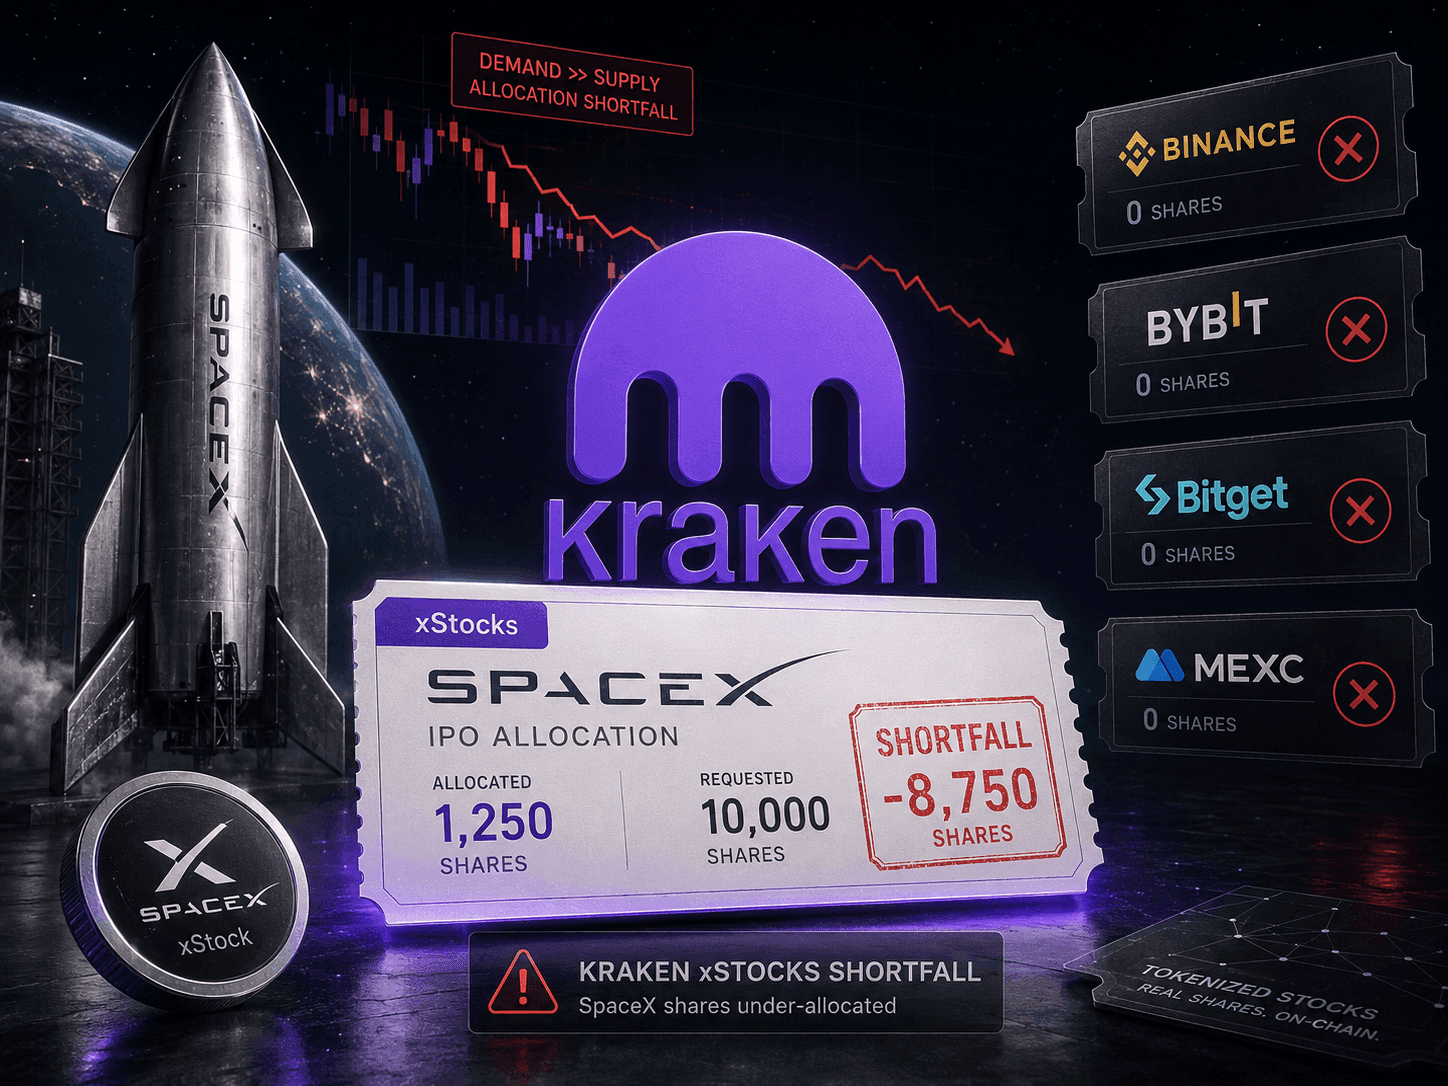
Why Binance, Bybit and Bitget Got Zero SpaceX Shares: Kraken's xStocks Came Up Short
xStocks — Kraken's own tokenized-equity arm — couldn't source SpaceX shares, leaving Binance, Bybit, Bitget and MEXC with zero. Here's why.
March 30, 2026 6:35 PM
Tech Giants Lose $5 Trillion: Why Crypto Is Holding Steady (For Now)
The Magnificent 7 tech giants have wiped out $5 trillion in market value. While crypto prices remain stable today, historical trends suggest a potential shift.
March 24, 2026 4:06 PM
Circle (CRCL) Stock Plummets 17% on Stablecoin Yield Crackdown Fears
Circle Internet Group (CRCL) shares dropped 17% today following reports of a potential legislative crackdown on stablecoin yields. USDC remains pegged to $1 (for now).
October 13, 2026 10:18 PM
Papertrade loses $1.28 million on launch day: the reference price came from Hyperliquid
The perpetuals venue Papertrade launched on October 10 with leverage of up to 1,000 and drew its execution prices from the Hyperliquid order book. One trader moved the Ether price there by around three dollars and took between $1.28 million and $1.54 million out of the liquidity pool, according to several trade publications.
October 11, 2026 1:37 PM
Hyperliquid (HYPE): $14.58 Million From USDC Earnings Flows Into the Buybacks, and What to Watch Now
Since the start of October, Hyperliquid has paid for its HYPE buybacks not only out of trading fees but also out of the earnings on its USDC reserves. The first payment came to around 14.58 million USDC, while the price sits 13 percent below its record.
October 2, 2026 10:26 AM
Evernorth Brings 473 Million XRP to the Nasdaq: Stock or Coin?
The shareholders of Armada Acquisition Corp. II approved the merger with Evernorth on September 30. From October 8, a company holding around 473 million XRP is to trade on the Nasdaq under the ticker XRPN, and for investors in Germany a tax question hangs on it.
September 26, 2026 1:11 AM
Funding Rate on Perpetual Futures: How to Calculate What Your Position Really Costs
A rate of 0.01 percent per interval sounds like nothing and works out at almost 11 percent of the notional value over a year. This guide walks through the calculation, the timestamp effect and the way leverage multiplies the burden.
September 24, 2026 1:24 PM
NEAR Falls Almost 8 Percent After a 62 Percent Week: What to Check on Perps, Buying Route and Holding Period
NEAR Protocol loses up to 7.9 percent on September 24, 2026 and is still more than 55 percent higher over the week. The rally was carried by a confidential perp offering via Hyperliquid, which raises questions of its own on buying route, leverage and holding period in Germany.
More from CryptoTicker