
ESMA Places Perpetual Futures Inside the CFD Perimeter: 2:1 Leverage for Retail Clients in the EU
ESMA stated on February 24, 2026 that perpetual futures are likely to fall under the CFD measures, and with them under a leverage cap of 2:1 for retail clients. The Hyperliquid Policy Center wants that settled differently, and filed its case as the MiCA review closed on September 30.




Which topics should we dive deeper into?
Select what genuinely interests you. Your picks feed directly into our editorial planning.
Crypto news that's actually worth your time.
Weekly. 60 seconds. Carefully curated by our editors: no hype, no promo flood, no spam.
Whether you, as a retail client in Germany, may trade perpetual futures with two times leverage or with fifty times leverage hangs on a question of classification in European supervisory law. It runs as follows: are these contracts contracts for difference within the meaning of the existing EU measures? If they are, a leverage cap of 2:1 applies to retail clients. On February 24, 2026, the European Securities and Markets Authority, ESMA, stated in a public notice that derivatives marketed as “perpetual futures” or “perpetual contracts” are likely to fall within that scope. On September 30, 2026, the final day of the consultation period for the review of the MiCA regulation, the Hyperliquid Policy Center filed a submission with the European Commission that asks for exactly this classification to be settled differently.
For you, more rides on this than a question of terminology. The classification determines what leverage a provider may offer you at all, whether your losses are capped at the balance you have paid in, at what point a position is closed out, and which venues are allowed to take you on as a client in the EU.
What the Hyperliquid Policy Center filed with the European Commission on September 30
The Hyperliquid Policy Center, or HPC, is an advocacy body from the orbit of the decentralised trading platform Hyperliquid. The submission of September 30, 2026 is, by the organisation's own account, its first statement on a rulebook outside the United States. It is addressed to the European Commission, which had been gathering responses through its targeted consultation on the MiCA review since May 20, 2026.
At the heart of the submission is a shift of competence. The HPC asks the Commission to confirm, building on ESMA's existing guidance, that perpetual futures fall under the financial markets directive MiFID II, irrespective of the system in which they are recorded and of the underlying to which they refer. MiFID II is the European rulebook for investment firms, trading venues and financial instruments, derivatives among them. The organisation stresses explicitly that no new legislation is needed for this, and that a clarification would suffice.
The load-bearing argument is an economic one. In the HPC's view, supervisory classification should depend on the structure and the economic characteristics of a product and not on the technology used to record it. Jake Chervinsky, who heads the HPC, condensed that thought in the submission into the proposition that an instrument's economic properties, and not the ledger in which it is recorded, ought to decide its classification.
ESMA notice of February 24, 2026: perpetual futures inside the CFD perimeter
The supervisor itself provided the occasion for the submission. A perpetual future is a derivative on an underlying which, unlike a classic future, has no expiry date and stays tied to the spot price through a recurring settlement payment. On February 24, 2026, ESMA published a public notice on the question of which derivatives fall within the scope of the national product intervention measures for contracts for difference.
The authority's message is clear on three points. First, the product name is immaterial: the fact that a contract is marketed as a “perpetual” says nothing about its legal classification. Second, neither the funding rate mechanism nor voluntary safeguards such as an insurance fund change anything about that assessment. Third, firms have to evaluate these products under MiFID II and under investor protection rules. On this reading, what is caught above all are contracts that provide leveraged exposure to crypto assets such as Bitcoin and are not settled exclusively by physical delivery.
A product intervention measure is a supervisory step by which an authority restricts or prohibits the distribution of a financial product to particular client groups. For contracts for difference, that step has existed in the EU since 2018, and it still takes effect today through the national measures of the member states.
The CFD rules in detail: 2:1 leverage, margin close-out and negative balance protection
What the CFD framework means for retail clients can be put in figures. ESMA adopted its measures for contracts for difference with effect from August 1, 2018 and set out tiered leverage limits in them: 30:1 for major currency pairs, 20:1 for other currency pairs, gold and major equity indices, 10:1 for other commodities and non-major equity indices, 5:1 for individual equities and other underlyings, and 2:1 for cryptocurrencies. The bottom tier is therefore precisely the one that covers crypto assets.
Four further requirements come on top. The measures prescribe a per-account margin close-out that harmonises the percentage at which a provider must close open positions; it sits at 50 percent of the required minimum margin. They require per-account negative balance protection, which caps a retail client's losses in total. They restrict incentives for trading contracts for difference. And they mandate a standardised risk warning that states the share of the provider's loss-making retail client accounts.
For a trader working with high leverage today, the gap between 2:1 and the figures common on large platforms is the real issue. The leverage cap determines how much capital you have to post for a position, and therefore also how far the price may travel before the forced close-out bites. If you want to know how the running costs of such a position break down, you will find the arithmetic in our guide to calculating the funding rate.
MiFID II instead of MiCA: the submission turns on structure and economic characteristics
MiCA governs the market for crypto assets in the EU, but it captures above all the crypto assets themselves along with the services around them. Derivatives on crypto assets are financial instruments and therefore belong to the world of MiFID II. That dividing line is exactly what the submission aims at: it wants the classification of perpetual futures determined through the existing derivatives framework rather than primarily through MiCA.
The practical difference lies in the catalogue of obligations. A trading venue under MiFID II needs a different authorisation, different organisational duties and different transparency duties from a crypto asset service provider under MiCA.
 Perp DEX compared: leverage, funding and liquidation
Counterparty risk: a perp venue is not itself the other side, according to the submission
The HPC does not dispute that perpetual futures are derivatives. What it disputes is that the restrictions dating from 2018 fit them unchanged. The reasoning starts from structure: with a contract for difference the provider itself acts as the client's counterparty, whereas on a venue for perpetual futures, as the organisation presents it, another market participant stands on the other side and not the platform itself. From that distinction the HPC concludes that the two products carry different structures and different risks, and that the measures should therefore not be transposed without adjustment.
The argument is not immaterial for investor protection. Where the provider is the other side, it has an interest of its own in the client's loss, and that very conflict of interest was one driver of the 2018 measures. If it falls away, the burden of justification shifts. Whether the Commission will follow that view is open. In assessing an individual provider, what counts in the end is how the contractual relationship is actually set up.
Funding rate, maintenance margin and liquidation threshold: what the submission wants published in advance
Alongside the classification, the HPC proposes concrete transparency duties. On this model, trading venues would publish their methodology for calculating the funding rate, their maintenance margins and their liquidation thresholds in advance. The funding rate is the periodic payment between the buy and sell side that ties the price of a perpetual future to the spot price. The maintenance margin is the minimum capital that has to cover an open position. The liquidation threshold is the point at which the platform unwinds a position by force.
A reporting proposal comes with it. In the organisation's view, publicly verifiable funding payments, liquidations and transaction activity could be taken into account by supervisors as features of market structure. The submission invites the Commission to examine whether such records can satisfy part of the reporting duties, provided the information is complete, reliable and accessible to supervisors.
These three figures matter to you even while the classification remains open. They determine what a position costs on an ongoing basis and when it is closed. How widely the terms differ between platforms is shown by a look at our comparison of perp DEX.
What the initiative means for investors in Germany
In the short term the submission changes nothing about your legal position. It is a statement in a consultation procedure, not a rule. What is in force today is ESMA's February notice: firms have to assess whether their products fall within the scope of the CFD measures, and where they do, the requirements apply, leverage cap of 2:1 for retail clients included.
In the medium term the question is which route lets you take leveraged crypto positions legally. If the supervisory line prevails, the offering for retail clients in the EU narrows to providers that meet the requirements. If the Commission follows the HPC's reasoning, a dedicated framework for perpetual futures could emerge, with transparency duties in place of a hard leverage cap. Both are documented possibilities, and neither is a forecast.
Why a leverage cap does not look like a block
A product intervention measure is addressed to the provider, not to you. It therefore rarely shows up as an error message in the trading window. It appears instead as a changed account classification, as fresh questions about your knowledge and experience, or as a provider that stops accepting clients from the European Economic Area altogether. Anyone who holds positions for months often notices such a change only at the next deposit.
Buying route and authorisation: how to check whether your perp platform is licensed in the EU
The check runs through the provider, not through the product. Look in the terms of use to see which company is your contractual partner and in which state it is based. Then establish whether that company holds an authorisation as an investment firm or as a crypto asset service provider in the EU, and whether clients from Germany are expressly admitted. Finally, see whether the provider displays a standardised risk warning stating the share of loss-making retail client accounts, because that warning is a hallmark of the CFD framework. Which regulated houses carry leveraged products for German clients is set out in our broker comparison.
 Regulated brokers for leveraged products
Tax: perpetual futures count as forward transactions, and the holding period does not apply here
The tax treatment follows the legal classification, and that is the uncomfortable part for you. The one-year holding period, which applies to direct purchases of coins through the rules on private disposals, does not apply to a derivative on a coin. Gains from forward transactions fall into investment income, and there is no period there after which a gain remains tax free.
Because the classification of individual products can be contested, and because platforms without an EU authorisation issue no tax certificate, this point belongs before your first trade and not in next year's tax return. Discuss the treatment of your positions with a tax adviser. For gathering records across the year, the tools from our comparison of crypto tax tools help, since they can extract funding payments and liquidations from the trading data.
Circle and the reserve rule: the second strand of the same consultation
The perpetuals submission is not the only one that arrived in the final days of the deadline. The stablecoin issuer Circle has, by its own account, called on the European Commission to retain multi-issuance of stablecoins, to recognise stablecoins regulated abroad, and to relax the duty to hold a share of reserves as deposits with commercial banks. Circle refers in this context to a share of 30 percent and justifies the demand with the counterparty risk that arises from such bank deposits.
Both submissions display the same pattern. What is attacked are individual points in the rulebook where, as the industry presents it, the rules meet structures they were not written for. Neither submission calls MiCA as a whole into question. For you as an investor the common denominator is availability: which stablecoins stay tradable in the EU, and what leverage you are allowed to trade with, are both outcomes of this detailed work.
The European Commission's report: what follows the September 30 deadline
The targeted consultation on the MiCA review ran from May 20, 2026 and ended on September 30, 2026. The original version of the documents named August 31 as the date; the Commission later extended the deadline on its own page to September 30. Thematically the survey covered, among other things, the scope and the definitions of the regulation, the rules for stablecoins, crypto asset service providers, decentralised finance applications, staking, NFTs and the legal treatment of individual tokens.
The Commission does not name a date for a legislative proposal in the public consultation documents. Months usually pass between the close of such a survey and a proposal. Until then, ESMA's February notice remains the yardstick that providers have to align with, and therefore the yardstick for your account too.
What you can read from the two dates
February 24, 2026 is the date from which firms had to assess. September 30, 2026 is the date from which the Commission is assessing. Between the two lies the phase in which providers adjusted, restricted or discontinued their offerings for European retail clients. If something about your account changed in that period, this is the likely reason.
Perpetual Futures and MiFID II: What to take away
- Establish who your contractual partner is and whether it is authorised in the EU. The leverage cap takes effect through the provider's authorisation. Our broker comparison shows which regulated houses carry leveraged products for German clients.
- Read up on your platform's funding methodology, maintenance margin and liquidation threshold before you open a position. Those are precisely the three figures the submission wants published in advance as a matter of obligation. The differences between platforms are set out in the perp DEX comparison.
- Set your record keeping up for forward transactions, not for the one-year holding period. Which tools extract funding payments and liquidations from the trading data is set out in the comparison of crypto tax tools.
(As of October 2, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Frequently asked questions about perpetual futures in the EU
Transparency note: This article was produced with the assistance of artificial intelligence and reviewed by our editorial team before publication. All figures and claims were checked against the primary sources linked in the text. The feature image was generated with AI.
Related articles
- Binance Launches FX Perpetuals With 100x Leverage: What Is Allowed in Germany
- CFTC Registers Coinbase Clearing for Fully Collateralised Derivatives: What Matters for Investors in Europe
- Cardano Slides Below $0.24: What ADA Holders Should Check on Leverage, Liquidation and Holding Period
- ESMA Calls for Advertising Rules on Crypto Influencers: Six Changes Now Sitting With the EU Commission
- Dogecoin Futures Hold $1.5 Billion in Open Leverage: What Investors Need to Know
Which topics should we dive deeper into?
Select what genuinely interests you. Your picks feed directly into our editorial planning.
Crypto news that's actually worth your time.
Weekly. 60 seconds. Carefully curated by our editors: no hype, no promo flood, no spam.

September 26, 2026 1:11 AM
Funding Rate on Perpetual Futures: How to Calculate What Your Position Really Costs
A rate of 0.01 percent per interval sounds like nothing and works out at almost 11 percent of the notional value over a year. This guide walks through the calculation, the timestamp effect and the way leverage multiplies the burden.

September 22, 2026 4:12 AM
Open Interest Climbs After the Short Squeeze: Why the Longs Are Paying Now
The short squeeze of September 21 wiped out $648 million in bearish bets, yet open interest rose instead of falling. A survey of our own across four exchanges shows the funding rate is positive on 24 of the 25 largest bitcoin perpetuals.
September 15, 2026 4:12 AM
Using Hyperliquid from Germany: What Applies to Your Funds Without a MiCA Licence
Hyperliquid is not entered in any EU register as an authorised crypto-asset service provider, and for perpetual futures a MiCA licence would be the wrong paperwork anyway. Here is what that means in concrete terms for your funds, your keys and your tax return.
September 9, 2026 1:26 PM
Bitcoin Options Expiry of September 25: What Holders of Leveraged Positions Should Know in Hindsight
Recap as of September 27, 2026: Bitcoin options worth $14.39 billion were due to expire on September 25, alongside Ether options worth $1.81 billion. This article describes the situation before that date, our own count of the derivatives market and what holders of leveraged positions should have checked at the time.
August 11, 2026 5:24 PM
Perp DEX Explained: How Funding Rate, Liquidation and Taxes Work on Perpetual Futures
Perpetual contracts run without an expiry date, and in exchange you pay funding for as long as you hold them. This article explains the mechanics behind perp DEX, the liquidation thresholds and the regulatory and tax framework in Germany.
September 30, 2026 10:13 PM
Robinhood Announces Perp Futures With 10x Leverage for US Customers: “Markets don’t work without traders”
Robinhood plans to offer eligible US customers perpetual futures on eight cryptocurrencies, with up to 10x leverage on Bitcoin and Ethereum. Nothing is tradable yet, and a different leverage cap applies in Europe.

April 8, 2026 11:46 PM
BXB Market Review 2026: Platform, Pricing, and What Traders Should Know
Considering using BXB Market? Here's a detailed look at their platform, account tiers, spread discounts, and trading conditions as of 2026.

May 31, 2026 12:25 PM
HYPE Token Hits $70 All-Time High: 4 Reasons for the Surge
Hyperliquid ($HYPE) hit a $70 all-time high, entering the top 10 cryptos. Here are the regulatory changes and revenue fundamentals driving the pump.
September 30, 2026 4:36 PM
Dogecoin Price Prediction: 28 Billion DOGE Make $0.098 the Level That Decides
Dogecoin trades at around $0.0973 on Wednesday midday and keeps failing at the zone at $0.098, where roughly 28 billion DOGE changed hands. At the same time $1.50 billion sits in open leveraged positions, and the tax authority's one-year period runs separately for every purchase.
September 30, 2026 4:14 AM
Bitcoin Price Before the Core PCE at 14:30 CEST: Will the $82,735 Level Hold?
At 14:30 CEST today the Bureau of Economic Analysis publishes the core PCE deflator for August, the inflation gauge the Fed anchors its 28 October rate decision to. Bitcoin stands at $83,329, less than $600 above its daily low, and anyone holding on leverage decides this morning.
September 24, 2026 10:11 PM

Bitcoin Price Prediction: What to Check on Levels, Holding Period and Leverage Before the October 28 Rate Decision
Bitcoin is trading at around $83,800, a third below its October 2025 high, while the sentiment index reads greed. Which dates, levels and deadlines over the coming weeks really decide your net gain, and which of them you steer yourself.
September 24, 2026 1:24 PM
NEAR Falls Almost 8 Percent After a 62 Percent Week: What to Check on Perps, Buying Route and Holding Period
NEAR Protocol loses up to 7.9 percent on September 24, 2026 and is still more than 55 percent higher over the week. The rally was carried by a confidential perp offering via Hyperliquid, which raises questions of its own on buying route, leverage and holding period in Germany.
September 24, 2026 4:16 AM
Trump-Xi Summit at the White House: The Crypto Positions to Check Before the Meeting
Xi Jinping is on a state visit to Donald Trump today, and the crypto market comes into the meeting carrying the gains of an exceptionally strong week. What to check on leverage, holding period and custody before the first headline runs.
September 12, 2026 1:29 AM

Is Polymarket Allowed in Germany? What the ESMA Report Says About Prediction Markets
ESMA has given prediction markets a chapter of their own in its risk report for the first time. It writes that event contracts require an authorisation in the EU that the large platforms do not hold.
August 26, 2026 7:34 AM
Coinbase Delisting on August 26: Ten Perpetual Futures Go, Open Positions Are Settled
Coinbase is removing ten perpetual futures from trading on August 26, 2026, among them the contracts on The Sandbox, Axie Infinity and Blur. Anyone leaving a position open does not sell it themselves but is settled at an average price from the final hour of trading.
September 19, 2026 4:11 PM
MiCA Consultation Closes September 30: What to Check and Submit Before Then
The European Commission is reviewing the MiCA crypto regulation and will accept submissions until September 30, 2026 at 23:59 CEST. Staking, DeFi, lending, stablecoins and custody are all under examination, and you can take part without a lawyer.
September 22, 2026 10:15 PM
Stablecoin Reserves: Why the ECB Wants the Bank Deposit Rule Scrapped
The European System of Central Banks filed its response to the MiCA review on September 22 and calls in it for an end to the requirement to hold 30 to 60 percent of stablecoin reserves as a bank deposit. What lies behind it, and what you can check on your own token.
September 12, 2026 10:11 PM
Crypto CFD or Buying Real Coins? How Leverage, Margin Calls and Tax Differ
With a crypto CFD you own a contract; with a direct purchase you own the crypto asset itself. From that one difference follow the 2:1 leverage cap, forced close-out, the tax burden and the question of who is liable for your money if things go wrong.
September 11, 2026 4:13 PM

How to Calculate Your Liquidation Price: When the Exchange Closes Your Leveraged Position
The liquidation price is the level at which your exchange force-closes a leveraged position. Here are the formula for long and short, a worked example, and the cost items that squeeze the buffer tighter in practice than the arithmetic suggests.
August 20, 2026 10:24 PM
MiCA Review: What the European Commission Could Change About the EU Crypto Rules
The European Commission has reopened MiCA for review after barely two years and is asking 86 questions covering the stablecoin interest ban, staking, lending and DeFi. Brussels is taking responses until September 30, 2026.
August 6, 2026 3:05 PM
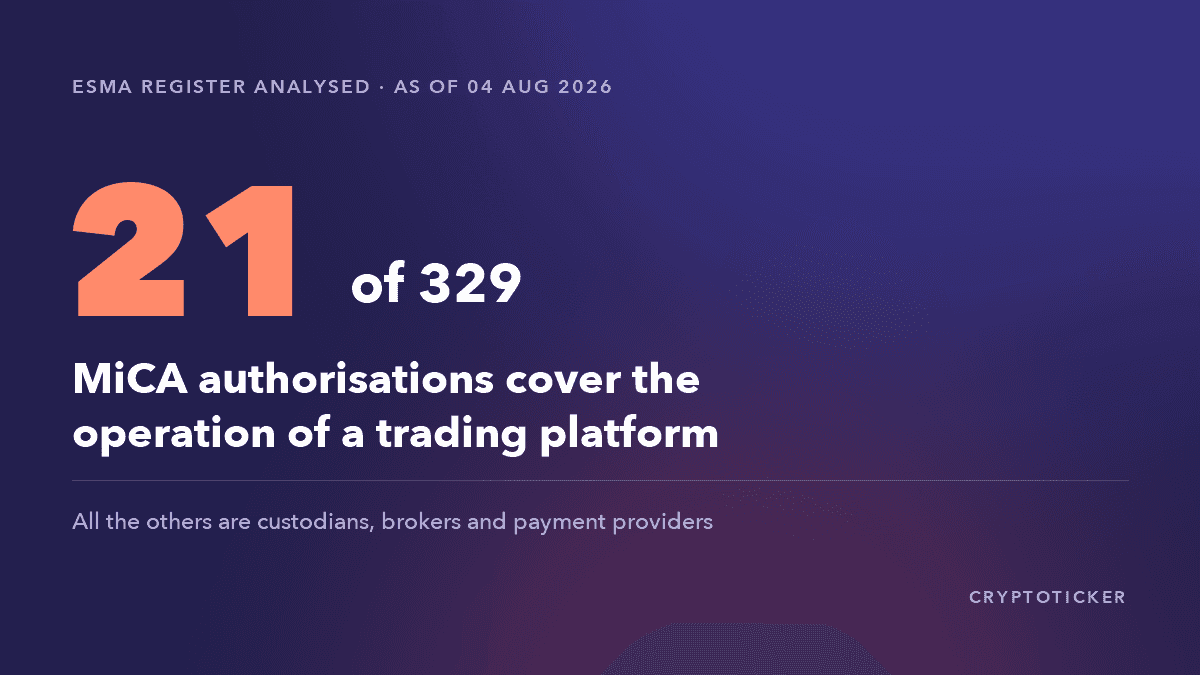
MiCA Register 2026: Only 21 of 329 Licences Are Real Exchanges
ESMA publishes the register of MiCA-authorised providers as an open file. We worked through all of it — and the result is not what the phrase “licensed crypto exchange” suggests.
September 29, 2026 10:33 AM
ESMA puts reverse solicitation on its 2027 watch list: what investors need to know about exchanges without an EU licence
ESMA presented its work programme for 2027 on September 28, 2026 and made reverse solicitation a supervisory priority. What that means if your coins sit with a provider without EU authorisation, and which three steps make sense now.
September 19, 2026 4:02 PM
Binance MiCA License: Did Lagarde Personally Block Binance From the EU?
The WSJ says ECB chief Christine Lagarde asked Greece not to approve Binance's MiCA license. Here is what happened, and why the ECB had no formal say.
August 21, 2026 7:17 AM
Checking a MiCAR White Paper: What the First Published MiCA Penalty Against Bitpanda Means for Investors
Austria's FMA has fined Bitpanda GmbH 70,000 euros because a crypto-asset white paper was filed late and advertised before it had been published. We explain what rights this mandatory document gives you, and called up all 972 white papers held in the ESMA register to see whether they can be reached at all.
August 19, 2026 7:17 PM
MiCA Register of Stablecoin Issuers: 23 Authorised Firms, 43 White Papers and Two Dead Links
The official ESMA register lists 23 authorised issuers of e-money tokens and 43 notified white papers. We called up every document address stored there ourselves and show where the record leads nowhere.
More from CryptoTicker