
Staking Taxes in Germany: The Inflow, the 256-Euro Threshold and the Holding Period
Staking is taxed twice: once when the reward arrives and once when you sell it later. This article explains both moments, the threshold of 256 euros, the separate twelve-month period and what applies to liquid staking, restaking and staking ETPs.




Which topics should we dive deeper into?
Select what genuinely interests you. Your picks feed directly into our editorial planning.
Crypto news that's actually worth your time.
Weekly. 60 seconds. Carefully curated by our editors: no hype, no promo flood, no spam.
The key points at a glance
- Two moments, two taxes: staking is taxed when the reward arrives and taxed again when you later sell it. Anyone thinking only about the sale is missing half the picture.
- The inflow is income from other services under Section 22(3) of the German Income Tax Act (EStG), valued at the market price at the moment it arrives and charged at your personal tax rate.
- A threshold of 256 euros a year. It is a threshold, not an allowance: one euro above it makes the entire amount taxable. It has nothing to do with the 1,000 euros under Section 23.
- Twelve months, not ten years. The extended holding period has been cleared up by the tax authorities. Every reward you receive starts a period of its own on the day it arrives.
- The market value on arrival becomes your acquisition cost. That is why a later sale is taxed only on the change in value since the inflow, and not on the whole proceeds.
Why staking is taxed twice
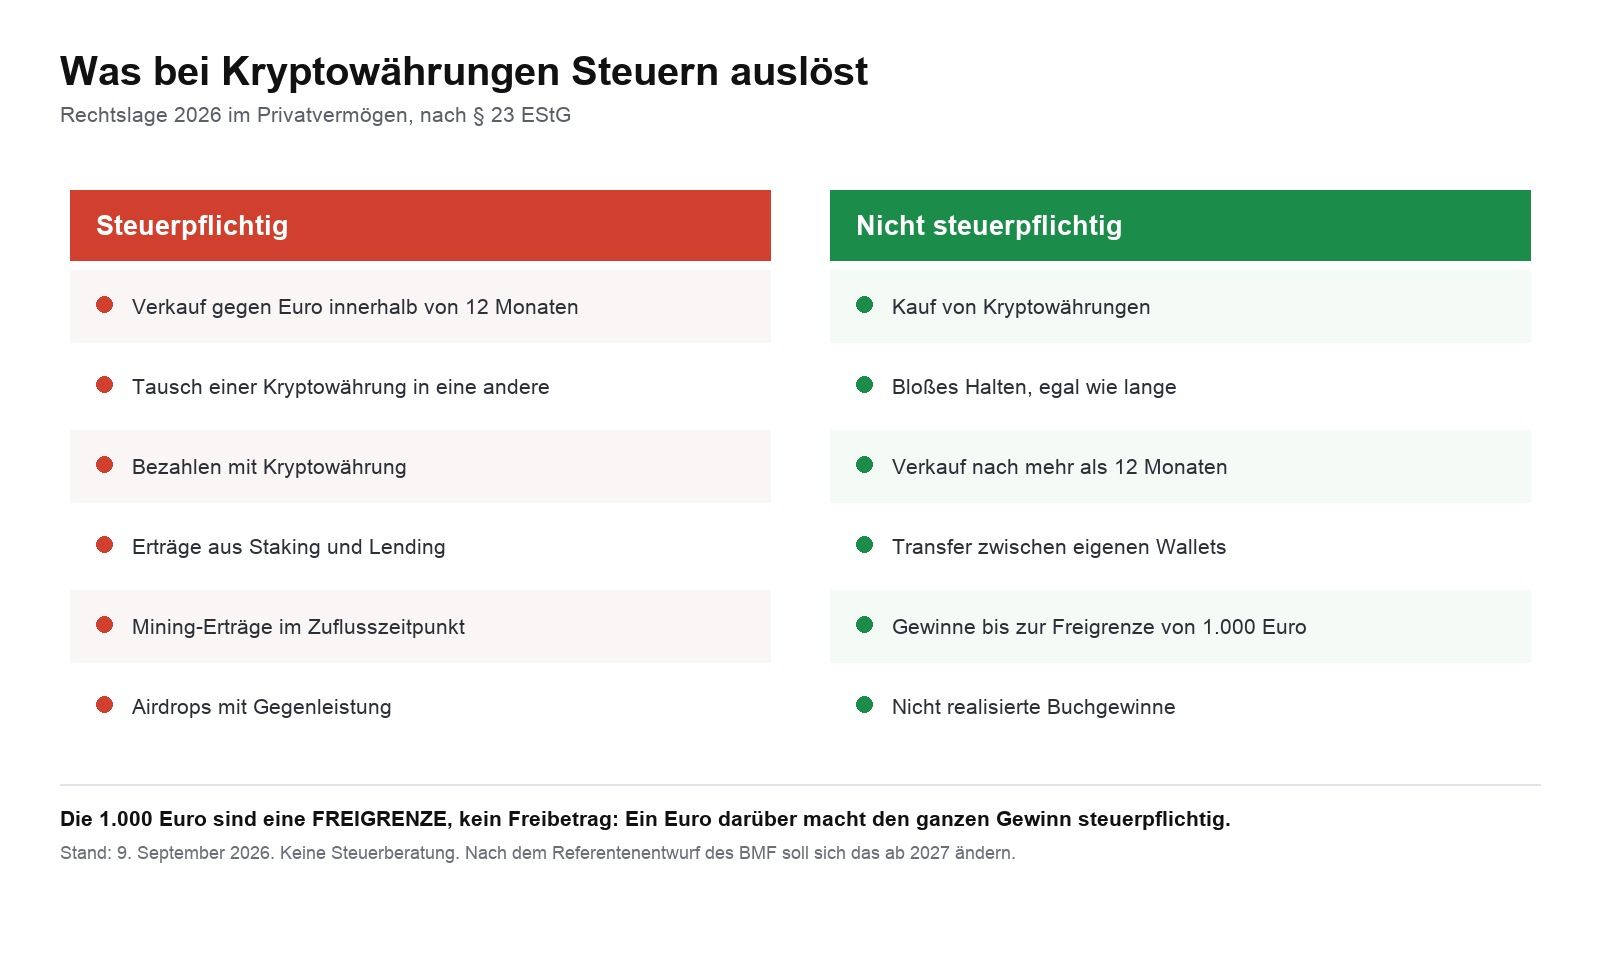
With staking, the most common misunderstanding concerns the number of taxes rather than their size. Two separate events take place, and for tax purposes they sit in different worlds.
The first event is the reward itself. It reaches you without you selling anything. In tax terms this is a service for which you receive a consideration: you make capital available to the network, and the network pays for it. That income belongs to the other services covered by Section 22(3) of the German Income Tax Act.
The second event is the sale of the coins you received. Section 23 applies to it, the same rule as for coins you bought: taxable within twelve months, tax-free after that.
Between the two sits a bridge that ruins a lot of calculations: the market value at the moment of the inflow is also the acquisition price for the second event. If you receive a reward worth 100 euros and sell it later for 130 euros, you pay tax once on 100 euros as other income and once on 30 euros as a capital gain. Not twice on 130.
The inflow and the 256-euro threshold
What counts is the moment you can dispose of the reward. At an exchange that is the credit to your account, with your own node it is access to the address. Valuation uses the price at that moment, not the price at the end of the year and not the price when you sell.
These earnings carry a threshold of their own, 256 euros per calendar year. It is regularly confused with the 1,000-euro threshold under Section 23, yet it covers a different area and a different pot. Both are thresholds and neither is an allowance: with 255 euros of staking income you pay nothing, with 257 euros you are taxed on 257 euros.
The threshold applies to all other services in a year taken together. If you run lending alongside staking, you add both up before you compare.
Which staking event triggers what
| Event | Type of tax | Legal basis | Threshold and period |
|---|---|---|---|
| Putting coins into the stake | no taxable event | — | the twelve-month period of the staked coins keeps running |
| Reward arrives | other income | Section 22(3) EStG | threshold of 256 euros a year, market value at the moment of arrival |
| Holding the reward | no taxable event | — | its own twelve-month period from arrival |
| Selling the reward within twelve months | private disposal | Section 23 EStG | threshold of 1,000 euros, separate pot |
| Selling the reward after twelve months | tax-free | Section 23 EStG | no upper limit |
| Withdrawing the staked coins (unstaking) | no taxable event | — | not a disposal |
| Swapping the reward for another cryptocurrency | disposal and acquisition at once | Section 23 EStG | a fresh period starts for the coin you receive |

The twelve-month period in staking
Every single reward starts a period of its own on the day it arrives. Anyone collecting rewards daily accumulates three hundred and sixty-five separate deadlines over a year. That sounds impractical, and it is, but it is the legal position, and it is the reason why hardly anyone keeps track of staking without a tool.
The worry that staking stretches the holding period of the staked coins to ten years has been laid to rest. It came from an older reading of Section 23(1) no. 2 sentence 4 EStG. The tax authorities do not apply it to crypto assets. Twelve months remain the rule, for the staked coins as much as for the rewards. We have written up the dispute in detail in our comparison of the two tax models.
What applies to which kind of staking
Staking is an umbrella term for very different processes. For tax purposes they differ mainly on one point: do you receive a reward, or do you receive a different asset?
| Form | What happens for tax | Basis | What to watch |
|---|---|---|---|
| Solo staking with your own node | reward as other income | Section 22(3) EStG | at a substantial scale, business status may be examined |
| Staking through an exchange | reward as other income | Section 22(3) EStG | the inflow is the credit; the exchange report is not binding |
| Staking pool | reward as other income | Section 22(3) EStG | the pool fee reduces the inflow |
| Liquid staking with tokens such as stETH | disputed: a swap or merely a receipt | Section 23 or Section 22(3) | treated as a swap, the tax arises as soon as you enter |
| Restaking | an extra layer of rewards, same classification | Section 22(3) EStG | two reward streams, two valuations per inflow |
| Staking ETP in a securities account | investment income or disposal, depending on the structure | Section 20 or Section 23 | distributing and accumulating products are treated differently |
| Lending instead of staking | interest as other income | Section 22(3) EStG | the same threshold of 256 euros, one shared pot |
If you stake through an exchange, you should also know how its tax report is built. Which platforms deliver usable exports is set out in our comparison of crypto exchanges. We have taken apart the two tax traps that come with selling staked coins in a separate article.
Two of those rows are not conclusively settled. With liquid staking, much depends on whether the token you receive counts as an asset in its own right or merely as proof of the coins you deposited. The details are in our article on restaking and liquid staking. With exchange-traded products the structure decides, and we have written up the differences between distributing and accumulating.
A worked example with real numbers
Suppose you staked Ethereum in 2026 and received rewards worth 800 euros in total, spread across the year and each valued at the price on the day it arrived. Your personal tax rate is 30 percent.
- Step one, the inflow. 800 euros sits above the threshold of 256 euros. The taxable amount is then the full 800 euros, and not the 544 euros above the line. At 30 percent that comes to 240 euros of income tax.
- Step two, the sale. You sell the rewards after eight months for 1,100 euros in total. The acquisition cost is the 800 euros from step one. The capital gain amounts to 300 euros.
- Step three, the second threshold. The 300 euros stay below the 1,000-euro threshold under Section 23. If you had no other private disposals in the same year, this part remains tax-free.
- Result: 240 euros of tax on 1,100 euros of inflow and proceeds. Waiting twelve months would have left the same 240 euros in place, because waiting does not remove the tax on the inflow.
That last point is the practical lesson: waiting helps with the sale, not with the inflow. Anyone who stakes has a tax charge every year, even without a single sale. And that charge is in euros, while the reward sits in coins.
What you have to document
The record-keeping duty is stricter for staking than for simply buying and holding, because the tax office needs two values per event instead of one. Without records the reward cannot be valued, and an estimate rarely lands in your favour.
- Per inflow: date, time, quantity, the price at the moment of arrival and the euro amount that follows from it. The price needs a source you can name, and that source should stay the same across the year.
- Per sale: date, quantity, proceeds and the allocation showing which inflows were sold. With daily rewards this is the point where manual work ends.
- For the period: the order. If you do not fix and document which coins were sold first, you cannot prove the twelve-month period.
- Platform records: account statements and transaction overviews. They are not binding for tax purposes, but they are the evidence that the inflow happened.
How to keep that up without a spreadsheet is set out in our article on documenting staking rewards. Which tools value the inflows automatically is shown in our comparison of crypto tax tools.
What is set to change from 2027
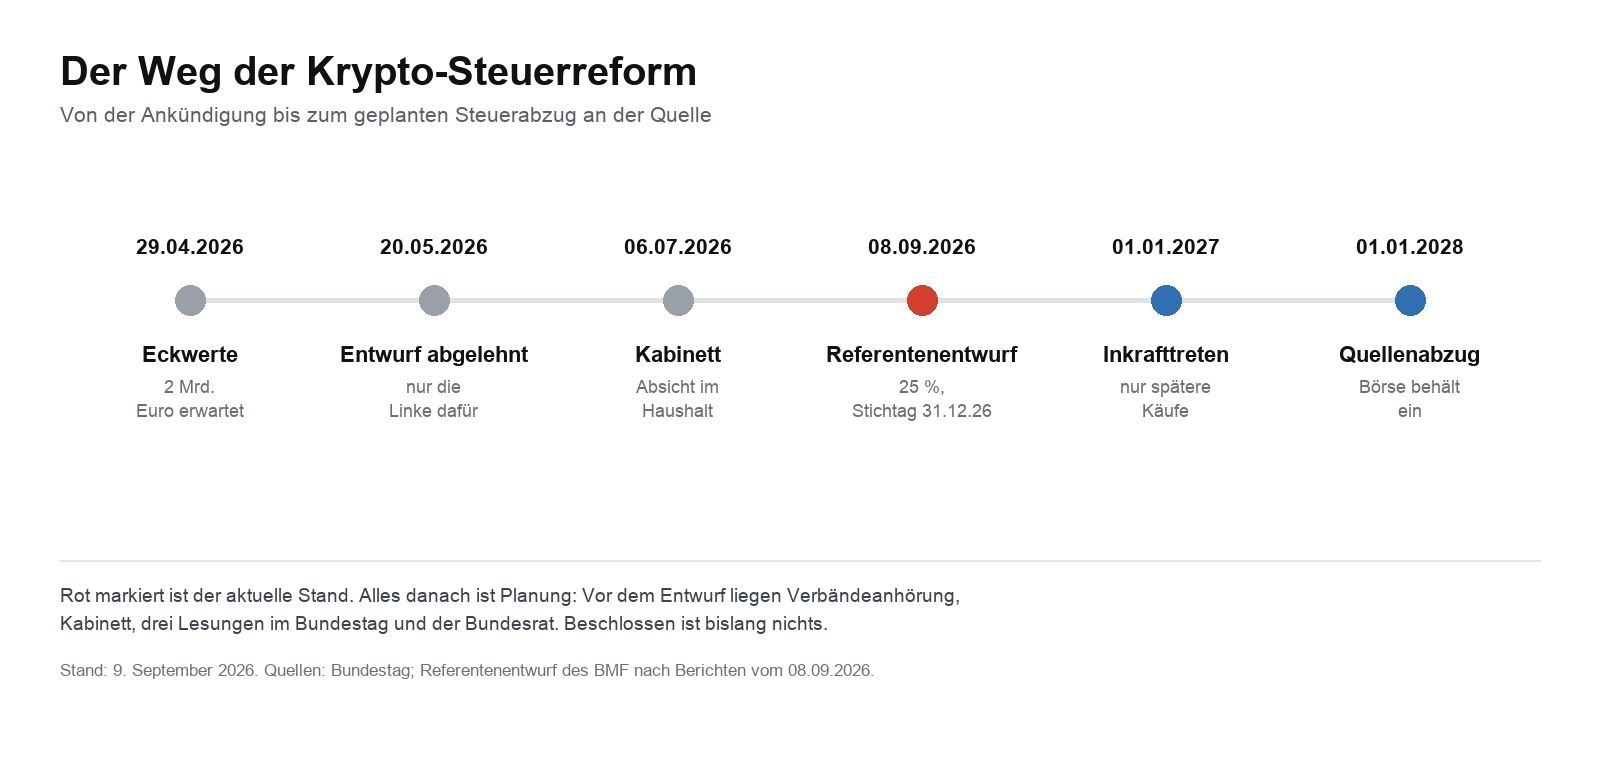
A ministerial draft would charge gains from the sale of crypto assets with the flat-rate withholding tax of 25 percent, for purchases made after December 31, 2026. The process is running, and no law has been enacted. The Income Tax Reform Act 2027, approved by the cabinet on September 2, 2026, contains nothing on crypto assets.
For staking, the decisive question remains open. Taxation of the inflow under Section 22(3) is left untouched in the drafts known so far. Were the flat-rate tax to arrive for disposals, stakers would face two different tax rates within one process, the personal rate on the inflow and the flat rate on the change in value. The current state of play is in our article on crypto tax in Germany.
Common questions about staking and taxes
Are staking rewards tax-free if I do not sell them?
No. The tax arises on the inflow and not on the sale. Anyone receiving rewards worth more than 256 euros in a year and selling none of them still has taxable income.
How high is the tax on staking?
Your personal income tax rate applies, so between 14 and 45 percent, plus the solidarity surcharge and church tax where they are due. The flat-rate withholding tax of 25 percent does not apply here.
Where do I enter staking income in my tax return?
In Annex SO, in the section for services. The sale of the rewards belongs in the same form, but in the section for private disposals. The details are in our article on where you enter what.
Does the threshold of 256 euros apply per coin?
No, it applies once a year to all other services taken together. Staking on three different networks plus lending gives one combined amount.
Does staking extend the holding period to ten years?
No. The tax authorities do not apply that reading to crypto assets. Twelve months remain the rule.
What happens when staked coins are sold at a loss?
Losses from private disposals can only be offset against gains from the same type of income, not against salary and not against investment income. The inflows you have already taxed are unaffected.
Do I have to list every single reward separately?
Each inflow has to be valued on its own. In the return itself the total is usually stated, while the itemised list goes into the annex as evidence. With daily rewards there is no way around it.
Sources and status
- Federal Ministry of Finance circular of March 6, 2025, on individual questions of the income tax treatment of certain crypto assets
- Federal Fiscal Court, judgment of February 14, 2023, case number IX R 3/22, on the asset status of crypto assets
- Section 22(3) and Section 23 of the German Income Tax Act
- Details of the ministerial draft based on reporting of September 8, 2026. An official full text is not available so far.
(As of September 10, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy. It does not replace tax advice either: with liquid staking, restaking and exchange-traded products the classification is not conclusively settled, and a question to your adviser is worth the time.)
Transparency note: This article was produced with the assistance of artificial intelligence and reviewed by our editorial team before publication. All figures and claims were checked against the primary sources linked in the text.
Related articles
- Bitcoin for a gift card: what paying with crypto means for your holding period
- Selling bitcoin privately: the tax in Germany and the records you need
- German Crypto Holding Period Set to Go After All: A Separate Draft Targets Purchases From 2027
- Crypto Holding Period and Grandfathering: Why December 31, 2026 Becomes the Cut-Off in Germany's Draft Bill
- Germany's Crypto Holding Period: What Happens Now Signing for Petition 201716 Closed on September 15
Which topics should we dive deeper into?
Select what genuinely interests you. Your picks feed directly into our editorial planning.
Crypto news that's actually worth your time.
Weekly. 60 seconds. Carefully curated by our editors: no hype, no promo flood, no spam.

September 27, 2026 1:17 PM

Dogecoin Price: What to Check on Holding Period and Custody Before the Year End
The Dogecoin price stands at $0.0977 on September 27, 2026 and has barely moved in a day. That calm is exactly the moment to work through the holding period, the reporting duty from 2026 and custody without any time pressure.

September 9, 2026 4:13 PM

Bitcoin 29 Percent Below Last Year: Which Crypto Losses You Can Still Use Before the One-Year Holding Period Expires
Nine out of ten major crypto assets trade lower today than exactly twelve months ago, Bitcoin alone by 29.2 percent. We measured the price series ourselves and show why the purchase date alone decides the tax value of your loss.
August 11, 2026 9:13 PM
Germany's Crypto Holding Period Faces Abolition: What Petition 201716 and the Draft Bill Mean for Your Tax
Petition 201716 calls for the one-year holding period for crypto assets to be kept and will be heard in public by the Bundestag's Petitions Committee on 12 October 2026. Correction of 8 October: the reform was not decided by the cabinet in July. A draft bill of 30 September would end the holding period for crypto acquired after 31 December 2026, and the cabinet is due to take it up on 14 October.
September 26, 2026 1:19 AM

Germany’s Crypto Holding Period Is Wobbling: What to Check Before December 31
A CDU member of the Bundestag makes it plain: the coalition agreement does not guarantee that the one-year holding period for crypto assets will survive. What that means for purchases made before the planned cutoff date of December 31, 2026.
October 6, 2026 10:24 PM

Germany's Crypto Holding Period Before the Petitions Committee on October 12: What Matters Now
The Bundestag's petitions committee debates the crypto holding period on Monday, October 12, 2026, from 12 noon in a public sitting, with federal government representatives on hand for questions. Two days later the cabinet is to decide on the draft bill that removes the one-year period for purchases from 2027.
September 24, 2026 1:13 AM
Solana DEX Trades Overtake the NYSE: What to Check on Swaps, Tax and Oversight
Solana's decentralised exchanges settled roughly 208 million trades in a single week and overtook the New York Stock Exchange for the first time. The figure is real, but it measures something other than the comparison suggests, and for German investors it carries tax duties that no provider takes on.
September 22, 2026 10:13 AM

Circle Lends Against Bitcoin via cirBTC: Why the Wrapper Can Cost You the German Holding Period
Circle launched loans against deposited bitcoin on September 21, 2026. In Germany, the detour through the cirBTC token is very likely a swap, and a swap restarts your one-year holding period.
October 19, 2026 4:15 AM
Crypto FIFO across several exchanges: each wallet counts on its own in Germany
Hold bitcoin on several exchanges and in wallets of your own, and the holding period is calculated per pot, not across the total holding. What paragraph 62 of the BMF guidance orders, and why 31 December 2026 hangs on it.
October 16, 2026 7:25 PM

Crypto holding period for Bitcoin: “That remains to be seen,” says the finance ministry
The federal cabinet did not adopt the draft abolishing the one-year crypto holding period on October 14, 2026; it is still stuck in inter-ministerial consultation. This overview sets out what applies today, which dates follow and why the December 31, 2026 cutoff has no force of law so far.
October 15, 2026 4:13 AM

Crypto holding period: the cabinet date passes without a decision, December 31 stays the cut-off
Germany's federal cabinet did not adopt the expected decision of October 14, 2026 to abolish the one-year crypto holding period; the draft is still in interdepartmental consultation. Until new rules arrive, gains stay tax free after one year of holding, and the December 31, 2026 cut-off named in the draft separates old holdings from new ones.
October 5, 2026 10:14 AM
Solana price 108.46 euros: a 2.4 percent gain in euros, a 2.5 percent loss in dollars: what to check now
Solana is quoted at 108.46 euros and $121.30 on Monday morning. That leaves a gain of 2.4 percent for 2026 in euros and a loss of 2.5 percent in dollars. The difference comes purely from the exchange rate, and in Germany it decides the holding period, the tax threshold and the figure that ends up on the tax return.
August 12, 2026 6:24 PM
Tokenized Stocks and Tax in Germany: When the One-Year Holding Period Applies and When the Flat Tax Bites
If you buy a tokenized stock, you often apply the crypto rule: hold for a year, then the gain is tax-free. For these products that assumption usually does not hold, and this article shows from the wording of the law which feature decides the tax regime and how to find it in the issuer documents.
October 9, 2026 1:18 PM

Bitcoin Tax: One Year Past the $126,080 Peak, Losses No Longer Count
Bitcoin trades at $82,558 on Friday morning, 34.5 percent below an all-time high that is now a good year old. Anyone who bought back then loses more than the prospect of a quick recovery when the one-year period expires: the tax value of the loss goes with it.
September 18, 2026 10:13 AM

Bitcoin and the German Exit Tax: What Applies When You Move Abroad
Anyone emigrating with Bitcoin expects an exit tax on unrealised gains and finds nothing of the sort in the statute. Where the real risks sit is decided at four points: residence, the holding period, the legal form of your investment, and automatic reporting from 2026.
August 21, 2026 4:24 AM
Forced Sale on a Crypto Exchange: Which Moment Counts for the Holding Period and What You Must Document
At Luno, Kraken and Valour the deadlines are running out, after which the provider realises the remaining holding itself. For tax purposes that is a disposal, and what governs it is the exchange's timestamp.
September 14, 2026 10:23 AM
Take Ethereum Profits or Wait Out the Holding Period? What the Price Jump Means for Your Tax Bill
Ether reached its highest level since the end of January on September 11, 2026, and many are asking whether to sell now. In Germany the answer hangs on the purchase date first: we work out which tranches are tax free and which of them are showing a gain at all.
September 9, 2026 4:22 PM
Crypto Tax in Germany: What Applies in 2026 and What Is Set to Change in 2027
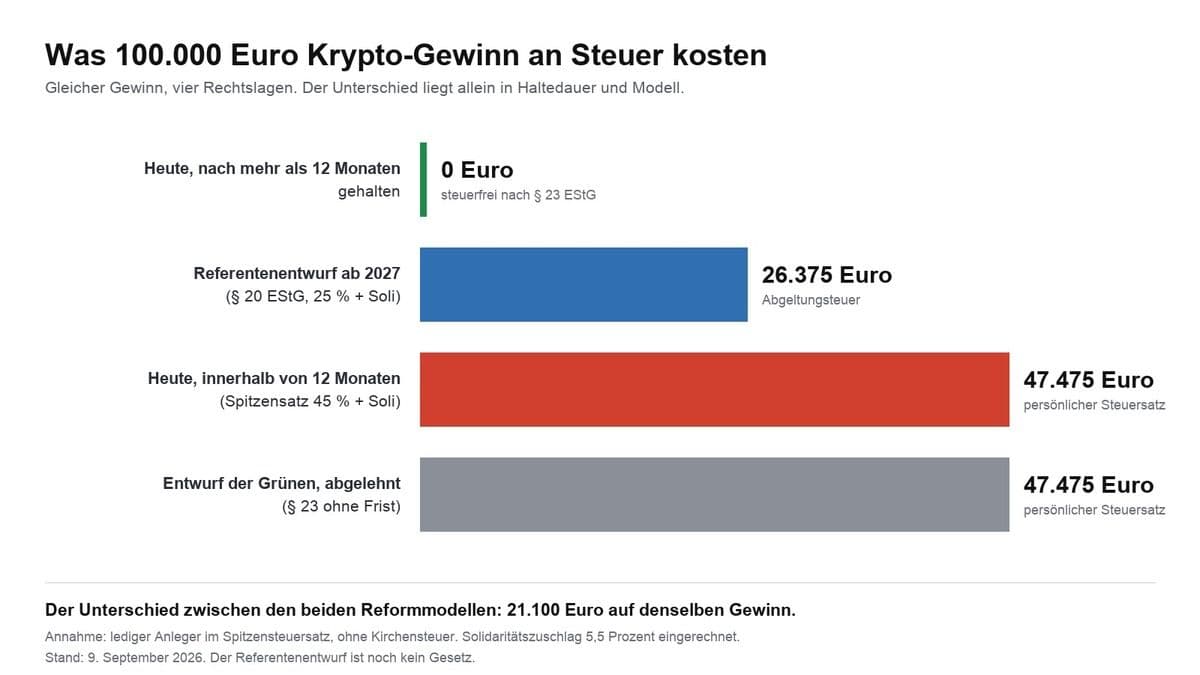
Crypto gains are tax-free after twelve months; before that your personal tax rate of up to 45 percent applies. What triggers tax, how the holding period is calculated, what happens with staking and losses, and what the draft bill would change from 2027.
September 16, 2026 7:12 PM

Borrowing Against Bitcoin Instead of Selling: When German Tax Still Applies
Posting Bitcoin as collateral for a loan is not a sale in Germany, because section 39 of the Fiscal Code keeps the coins attributed to you for tax purposes. Tax arises only when the collateral is liquidated, and then the one thing that decides the bill is how long you held the coins beforehand.
September 27, 2026 10:35 AM
Crypto Exchange Tax Report Wrong: How to Correct It Before the Tax Office Does
Missing acquisition costs, transfers booked as sales, holding periods restarted: your exchange's report is an aid and not proof. How to check it, how to correct it and which deadline is running.
October 2, 2026 4:39 AM

Donating bitcoin: when does the full market value count, when only the purchase price?
A bitcoin donation to a charitable organisation is deductible as a donation in kind, and the donation itself produces no taxable gain. The size of the deduction turns solely on whether a sale would have been taxable on the day of the transfer.
September 17, 2026 10:22 PM

Selling Bitcoin at a Loss and Buying It Straight Back: What That Does to Your Holding Period
Germany has no wash sale rule: the loss stays deductible even if you buy back immediately. The buyback, however, restarts the one-year period for every new unit.
September 23, 2026 7:22 PM
Solana Price Holds $114: What Holders Check Five Days Before Alpenglow
SOL stands at $114.55 on September 23, after a 17.7 percent gain in seven days and a 2.2 percent loss on the day. Two deadlines matter more than the daily move: Alpenglow opens on September 28, and every purchase made this week starts a holding period of its own.
September 12, 2026 1:21 PM
Declaring Crypto Gains Late in Germany: When a Voluntary Disclosure Under Section 371 Still Prevents Prosecution
From 2027 crypto service providers will report 2026 data to Germany's Federal Central Tax Office. If you never declared older gains, you should know when a voluntary disclosure still works and what makes it fail.
September 9, 2026 1:15 AM

Germany's Crypto Tax: 160 Million Euros for a 555-Billion Budget
The German finance ministry's draft bill puts a figure on the crypto tax for the first time: 160 million euros from 2028. What that number means in the 2027 federal budget, how 11.4 billion became 160 million, and what investors can read from it.
September 25, 2026 4:20 AM
Crypto as a Down Payment for a German Mortgage: What Banks Require
Since April 2023 a house in Germany can no longer be paid for in Bitcoin; section 16a of the Money Laundering Act bans it outright. Your crypto holdings still work as a down payment, provided you take the route through the euro and prove the origin without gaps.

September 24, 2026 1:34 PM
Cardano Slides Below $0.24: What ADA Holders Should Check on Leverage, Liquidation and Holding Period
Cardano has given back its move above $0.25 and trades around seven percent below the high of the past 24 hours. What that means for leveraged positions, the holding period of your tranches and the buying route under MiCA.
October 17, 2026 10:16 PM
Shiba Inu ten days before its record turns five: what matters now is the holding period
On October 27 the all-time high of Shiba Inu turns five years old, and the price stands 94.2 percent below it. For holders in Germany nothing about that date hinges on the price; it hinges on the one-year deadline in section 23 of the Income Tax Act.
More from CryptoTicker