
German Crypto Tax Return: Where to Enter Gains, Losses and Staking in Anlage SO
In Germany, crypto gains belong in Anlage SO, and staking and lending go in a separate section of the same form. Which lines of the 2025 form apply, when you do not have to enter anything, how to keep your losses and which deadlines are running now.

Which topics should we dive deeper into?
Select what genuinely interests you. Your picks feed directly into our editorial planning.
Crypto news that's actually worth your time.
Weekly. 60 seconds. Carefully curated by our editors: no hype, no promo flood, no spam.
Paying tax in the UK? Our UK crypto tax guide covers Capital Gains Tax at 18% or 24%, the £3,000 allowance and how to report to HMRC.
Updated on 24 October 2026: rewritten with the lines of Anlage SO 2025 from the official instructions, the filing deadlines for 2025 and 2026, a guide for ELSTER and the status of the planned reform.
In a German tax return, crypto belongs in Anlage SO. Gains and losses from selling, swapping and paying with crypto within one year of purchase go in lines 45 to 49 as well as 56 and 57 of the 2025 form; income from staking, lending, mining and airdrops goes in lines 14 to 21. If you held for more than a year, or your total gain from private sales stayed below 1,000 euros for the year, you do not enter a gain. Always report losses, otherwise they are lost.
These rules apply unchanged to your 2025 and 2026 tax returns. The draft bill of the Federal Ministry of Finance dated 30 September 2026 would only cover purchases from 2027, and the federal cabinet did not adopt it on 14 October 2026. The line numbers come from the official instructions for the 2025 income tax return on ELSTER. The figures for Anlage SO come from the free CryptoTicker tax calculator: it reads your exchange export, applies FIFO and shows the taxable gain and the exemption limit for each year.
Key facts at a glance
- Anlage SO, lines 45 to 49 plus 56 and 57: sales, swaps and payments with crypto assets held for no more than one year.
- Anlage SO, lines 14 to 21: staking, lending, mining, forging and airdrops, unless they belong to another type of income.
- 1,000 euro exemption limit: if your total gain from private sales in 2025 stayed below 1,000 euros, you do not have to enter it. For joint assessment the limit applies to each spouse.
- 256 euro exemption limit: staking and lending income has its own limit, also per person.
- Always enter losses: the tax office only records losses that are declared and offsets them against later gains; line 66 covers the carry-back.
- Deadlines: with a tax adviser, the 2025 return is due on 1 March 2027; the 2026 return without an adviser on 2 August 2027.
When crypto belongs in your tax return
The obligation depends on the individual transaction, not on your holdings. If you only buy and hold Bitcoin, you have nothing to report, no matter how much the price has risen. Only a disposal counts for tax purposes, and section 23 of the German Income Tax Act sets a holding period of one year.
These transactions belong in the return:
- Selling for euros within one year of purchase, if your total gain from all private sales in the year is 1,000 euros or more.
- Swapping one cryptocurrency for another within the period, including into a stablecoin and even if no euro ever changed hands.
- Paying with crypto, for example for a voucher or a service. For tax purposes, that is a sale.
- Staking rewards, lending interest, mining income and airdrops with a consideration, once they reach 256 euros in total for the year.
- Losses from sales within the period, so that you can offset them against later gains.
You need no line for buying, holding, transfers between your own wallets and exchange accounts, or sales after more than a year. Keep the records of purchase dates and transfers anyway: they prove that the holding period had expired.
Whether you have to file a tax return at all is often decided right here. Employees with more than 410 euros of income not subject to wage tax must file under section 46(2) no. 1 of the Income Tax Act, and a taxable crypto gain is always above that because of the exemption limit. Which transactions are taxable in detail is explained in our guide to crypto tax in Germany.
Crypto gains in Anlage SO: which line is for what
Anlage SO is the form for "other income" and has two sections that matter for crypto. For tax year 2025, the official instructions name these lines:
| Transaction | Anlage SO 2025 | What you enter |
|---|---|---|
| Staking, lending, mining, forging, airdrops | Services (Leistungen), lines 14 to 21 | Income at market value at the time of receipt, minus directly attributable costs |
| Loss from services | Line 22 | Decision on the carry-back to the previous year; the loss reduces gains from services |
| Selling, swapping or paying with crypto assets within one year | Private sales, lines 45 to 49 plus 56 and 57 | Sale price, acquisition costs and expenses, resulting in a gain or loss |
| Gold, silver, foreign currencies and other assets | Lines 52 to 57 | The same details; lines 56 and 57 are shared by crypto assets and other assets |
| Loss from private sales | Line 66 | Decision on the carry-back; the carry-forward runs through the loss assessment |
| Sale after more than one year | none | Enter nothing, keep the records |
Line numbers change from one form year to the next. A guide with fixed lines from 2022 or 2023 will therefore send you to the wrong field. What stays reliable are the section headings: "Leistungen" for income, "Private Veräußerungsgeschäfte" with the sub-item for crypto assets for sales. In ELSTER, the input screens guide you through these headings anyway.
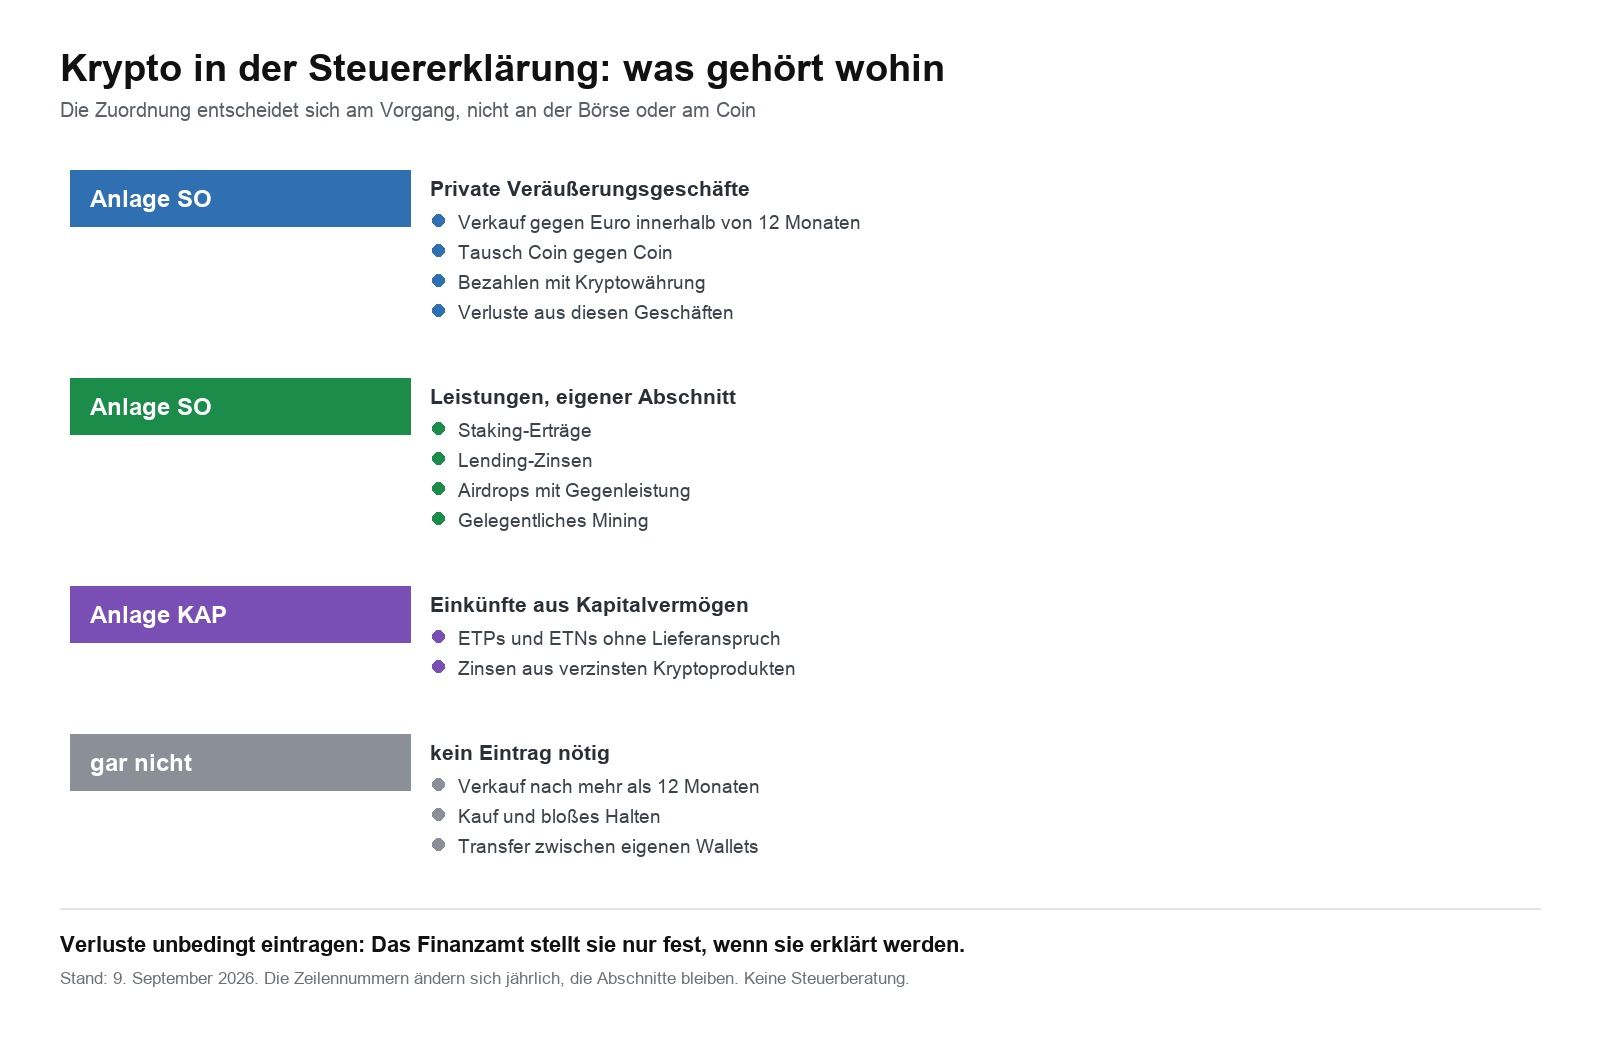
Anlage KAP only concerns crypto in special cases, more on that below.
German crypto tax return in ELSTER: step by step
The order saves time: collect first, then calculate, then enter. If you start entering first, you end up searching for prices from ten months ago in the middle of your return.
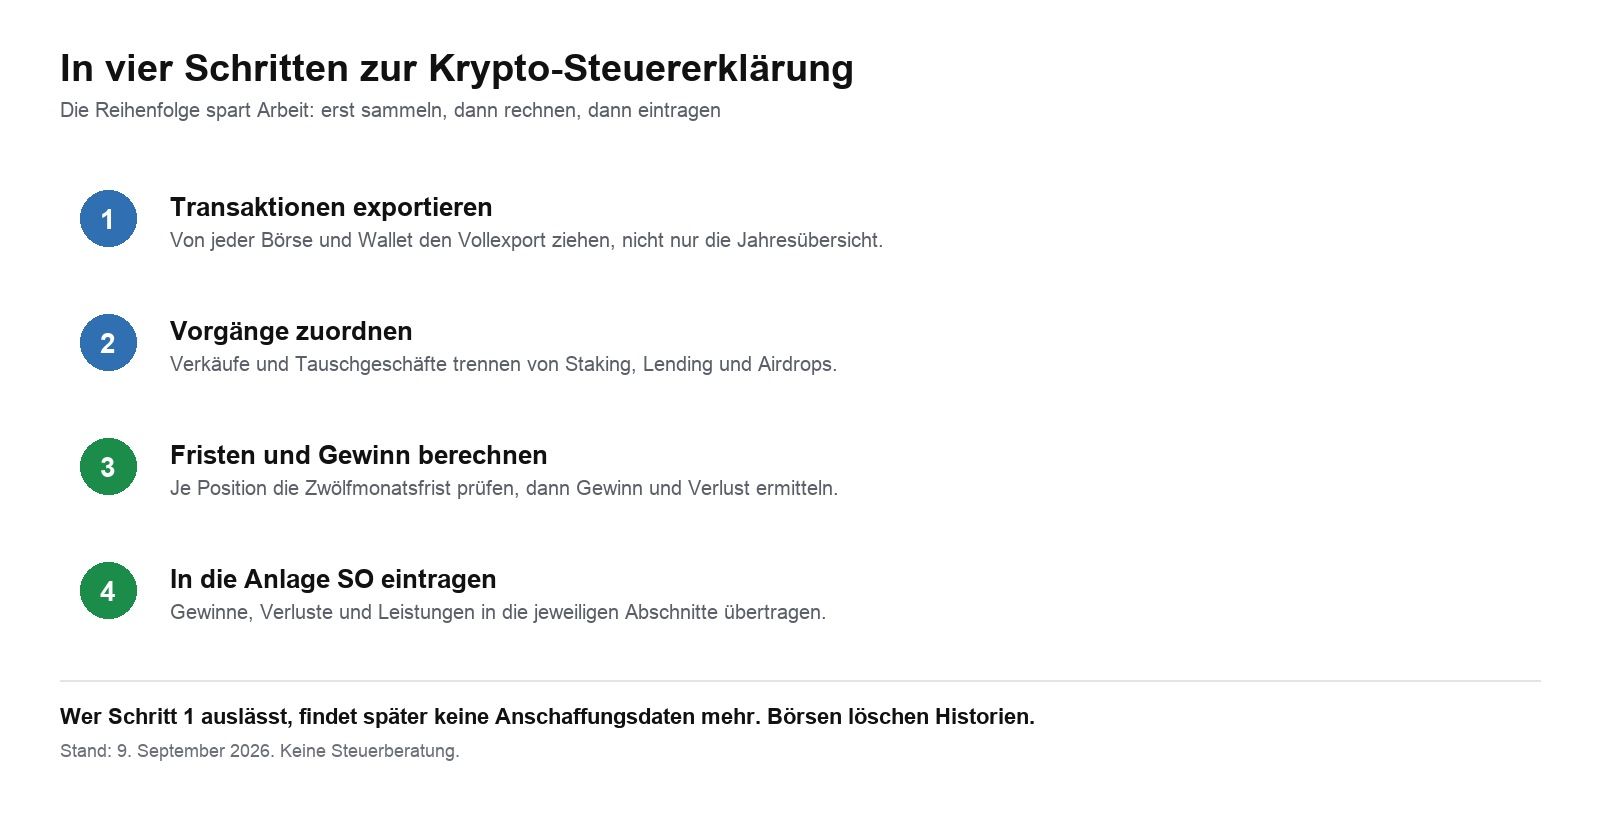
- Export your crypto transactions. Download the full transaction export from every exchange and wallet, not just the annual summary. You need every transaction with date, time, quantity, price and fee. Exchanges shorten their history or close down, which makes this the most important step.
- Separate the transactions. Sales and swaps go into the private sales section, staking rewards and lending interest into the services section. Mark transfers between your own wallets so that they do not count as sales.
- Calculate holding periods and gains. For every position sold, check whether more than one year has passed since the purchase. For several purchases of the same coin, the BMF letter of 6 March 2025 first requires specific identification; otherwise the coins bought first count as sold first (first in, first out), per wallet. Our article on FIFO across several exchanges and wallets shows how that works.
- Add Anlage SO in ELSTER. In Mein ELSTER, open the income tax return for 2025 and select Anlage SO among the forms. Enter crypto assets under "Private Veräußerungsgeschäfte" and income under "Leistungen".
- Enter the totals and keep the breakdown ready. The form takes totals. You do not have to send the transaction-by-transaction breakdown on your own initiative, but the tax office can request it. With many transactions, it makes sense to attach it right away.
- Check and submit. ELSTER runs plausibility checks. Save the transmission confirmation together with your export.
For step 3 you can use the CryptoTicker crypto tax calculator: it matches every sale with the purchases used up, shows the holding period and the taxable gain and applies the exemption limit for each year. You then transfer the totals to Anlage SO. If you want to combine several exchanges, DeFi and staking, you will find suitable programs in our crypto tax software comparison. The formula and the 2026 tax table are in Calculating crypto tax.
Staking and lending in the tax return
Staking rewards and lending interest are not capital gains but income from services under section 22 no. 3 of the Income Tax Act. You value them at market value at the time of receipt, i.e. at the price on the day the reward arrives in your wallet. That applies even if you never sell the coins.
If your income for the year stays below 256 euros, you do not have to enter it according to the official instructions. From 256 euros, the full amount is taxable, not only the part above the limit. The value at receipt also becomes the acquisition cost of the coins received, and a separate one-year period starts for them. If you sell them within that year, the sale also goes into the private sales section.
How to determine the value of daily rewards and what the BMF says about claiming is explained in our guide to staking taxes in Germany.
Reporting crypto losses in the tax return
Losses from crypto sales within the one-year period only reduce your tax if you declare them. You enter them in the same place as gains, in the private sales section, as a negative result.
Under section 23(3) sentences 7 and 8 of the Income Tax Act, they can only be offset against gains from private sales, including gains from gold or foreign currencies, but not against salary or share gains. What remains can be carried back one year or forward indefinitely. You decide on the carry-back in line 66. Anyone who skips a loss year because no tax is due anyway gives away the offset against future gains.
An example: you lost 3,000 euros on Ether in 2025 and made 5,000 euros on Solana in 2026. If the loss is in your 2025 return, the tax office records it, and in 2026 you only pay tax on 2,000 euros. If it is missing, you pay tax on the full 5,000 euros in 2026.
Crypto derivatives, ETNs and futures: when Anlage KAP applies
Not every crypto investment belongs in Anlage SO. Futures, perpetuals and options on cryptocurrencies are forward transactions and fall under section 20 of the Income Tax Act, i.e. capital income with 25 percent flat tax plus solidarity surcharge. A German bank withholds the tax; with a foreign exchange you declare the income yourself in Anlage KAP. Details are in our article on tax on crypto futures and perpetuals in Germany.
For Bitcoin ETNs and ETPs in a securities account, the classification depends on how the product is structured. Depositary banks usually withhold flat tax and certify the income for Anlage KAP; whether section 23 applies to products with a delivery claim, as with Xetra-Gold, is not finally settled. More in our article on Bitcoin, savings plans and ETPs.
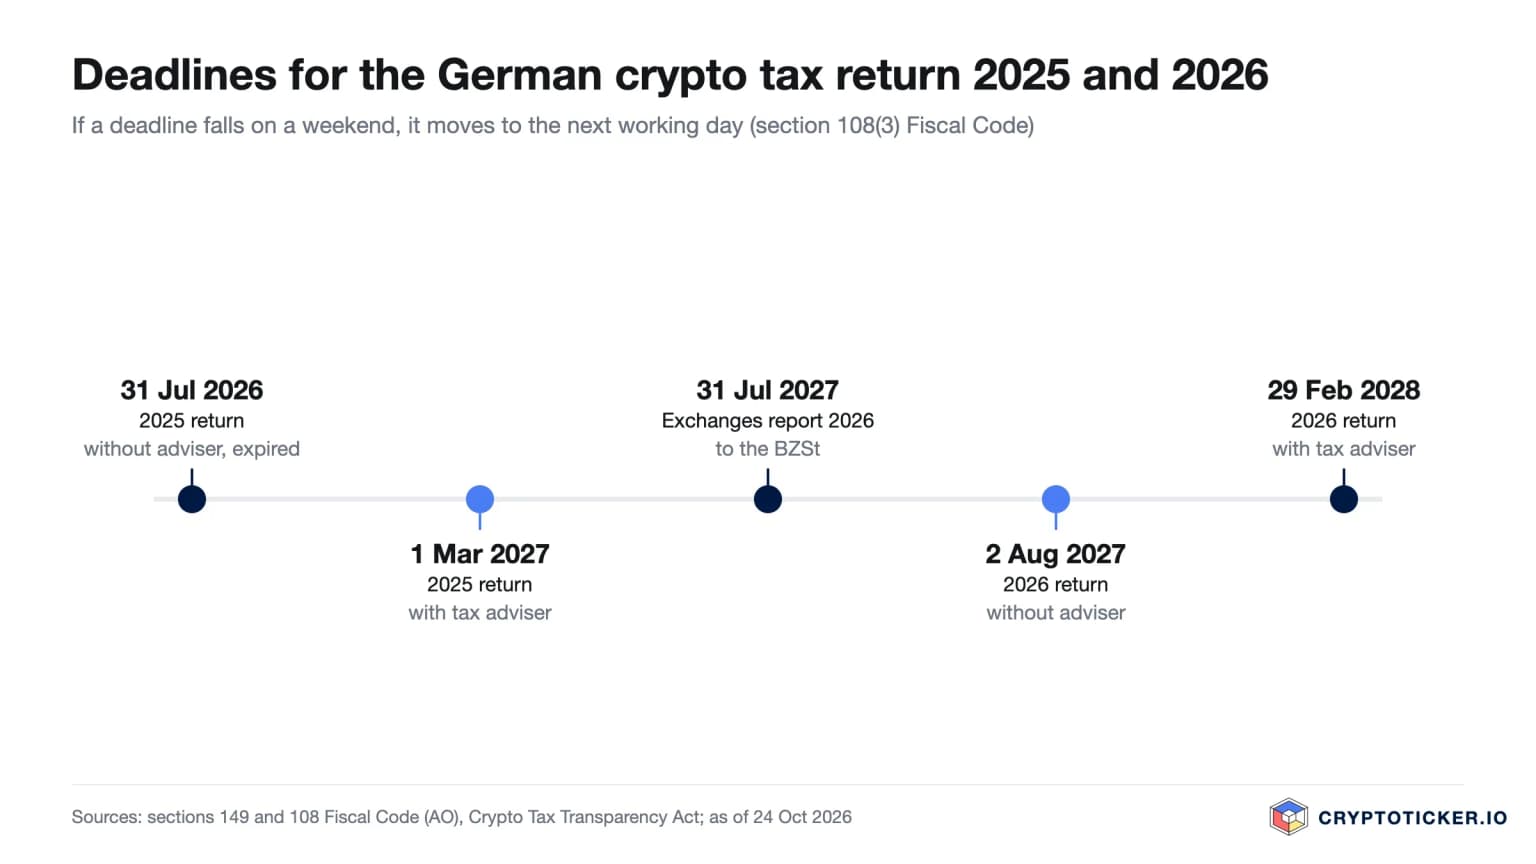
Deadlines for the German crypto tax return 2025 and 2026
If you prepare your return yourself, the 2025 return was due by 31 July 2026 under section 149 of the Fiscal Code. With a tax adviser, the deadline runs until the end of February of the year after next. Because 28 February 2027 is a Sunday, it ends on Monday, 1 March 2027 under section 108(3) of the Fiscal Code.
| Tax year | without tax adviser | with tax adviser |
|---|---|---|
| 2025 | 31 July 2026 (expired) | 1 March 2027 |
| 2026 | 2 August 2027, because 31 July is a Saturday | 29 February 2028 |
Missing the deadline risks a late filing surcharge. Under section 152(5) of the Fiscal Code, it amounts to 0.25 percent of the assessed tax minus prepayments and withheld taxes for each month or part month, at least 25 euros per month. If you are not obliged to file and do so voluntarily, for example to have a loss recorded, you have four years: the 2025 return can be filed until 31 December 2029.
How the tax office learns about your crypto transactions
Since 1 January 2026, crypto exchanges and custodians in the EU record their customers' transactions under the DAC8 directive. In Germany this is governed by the Crypto Tax Transparency Act (KStTG): providers report the data to the Federal Central Tax Office every year by 31 July, for the first time in 2027 for the year 2026. Your tax office can then check whether the reported sales appear in your return.
For 2025 and earlier years there is no automatic reporting yet. The tax office can, however, request information from exchanges in individual cases.
Anyone who does not report taxable transactions risks tax evasion under section 370 of the Fiscal Code, and for evaded taxes the assessment period is extended to ten years. A voluntary disclosure under section 371 is possible as long as the offence has not been discovered, and it must be complete. If you can no longer gather complete records, disclose that and make a traceable estimate instead of leaving transactions out.
Common mistakes in the German crypto tax return
- Forgetting swaps: Bitcoin for Ether or for a stablecoin is a sale. Many people only declare what ends up in euros in their bank account.
- Treating the exemption limit as an allowance: at a gain of 1,000 euros, the entire amount is taxable, not only the part above a threshold.
- Leaving out losses: without an entry, the tax office does not record a loss, and it is lost for later years.
- Counting your own transfers as sales: moving coins from the exchange to a hardware wallet is not a taxable event and does not interrupt the holding period.
- Applying FIFO across all exchanges: the order of consumption applies per wallet. Lumping all accounts together gets the holding period wrong.
- Valuing staking at the year-end price: what counts is the price on the day of receipt, not the price on 31 December.
- Forgetting fees: purchase fees increase the acquisition cost, sales fees reduce the gain.
What the planned crypto tax reform would change in the return
The draft changes nothing for the 2025 and 2026 tax returns. The draft bill of 30 September 2026 would turn crypto assets bought after 31 December 2026 into capital assets. Gains from them would then go into Anlage KAP instead of Anlage SO, and from 1 January 2028 exchanges would withhold the tax directly. Holdings you buy by the end of 2026 would stay in Anlage SO with the one-year period under the draft.
None of this has been passed. We track how things develop in the cabinet and the Bundestag in our overview of the status of the crypto holding period reform.
As of 24 October 2026. This article is not tax advice and does not replace individual advice from a tax adviser. Line numbers and deadlines change with every form year.
 Crypto exchanges compared: where you can buy bitcoin
Frequently asked questions about the German crypto tax return
Transparency note: This article was produced with the assistance of artificial intelligence and reviewed by our editorial team before publication. All figures and claims were checked against the primary sources linked in the text. The feature image was generated with AI.
Related articles
- Transferring crypto ETNs to a new broker in Germany: the loss pot only moves on request
- Swapping Bitcoin for gold: what it means for your holding period and tax
- 60.6 percent down in twelve months and only 12th by market value: what to check before your purchase anniversary
- Crypto GmbH: 25.6 percent tax from the first sale, nothing privately after a year: what matters now
- Crypto FIFO across several exchanges: each wallet counts on its own in Germany
Which topics should we dive deeper into?
Select what genuinely interests you. Your picks feed directly into our editorial planning.
Crypto news that's actually worth your time.
Weekly. 60 seconds. Carefully curated by our editors: no hype, no promo flood, no spam.

October 16, 2026 7:25 PM

Crypto holding period for Bitcoin: “That remains to be seen,” says the finance ministry
The federal cabinet did not adopt the draft abolishing the one-year crypto holding period on October 14, 2026; it is still stuck in inter-ministerial consultation. This overview sets out what applies today, which dates follow and why the December 31, 2026 cutoff has no force of law so far.
October 15, 2026 4:13 AM
Crypto holding period: the cabinet date passes without a decision, December 31 stays the cut-off
Germany's federal cabinet did not adopt the expected decision of October 14, 2026 to abolish the one-year crypto holding period; the draft is still in interdepartmental consultation. Until new rules arrive, gains stay tax free after one year of holding, and the December 31, 2026 cut-off named in the draft separates old holdings from new ones.
October 12, 2026 7:17 PM
Crypto Futures Tax in Germany: 25 Percent From the First Trade, No One-Year Rule
Crypto futures and perpetuals fall under Section 20 of the German Income Tax Act and therefore a flat 26.375 percent, with no holding period and no 1,000-euro exemption. Since the Annual Tax Act 2024, losses on them can again be offset without limit.
October 9, 2026 1:18 PM

Bitcoin Tax: One Year Past the $126,080 Peak, Losses No Longer Count
Bitcoin trades at $82,558 on Friday morning, 34.5 percent below an all-time high that is now a good year old. Anyone who bought back then loses more than the prospect of a quick recovery when the one-year period expires: the tax value of the loss goes with it.
October 8, 2026 4:17 AM

Crypto Holding Period: Without a Purchase Record the Tax Withheld Runs Ten Times Too High
The consultation on Germany's crypto tax bill closed on October 6 and the cabinet is to adopt it on October 14, with tax advisers, banks and the Bitcoin Bundesverband having filed their objections. The sharpest concerns everyone whose purchase data the selling platform does not hold: one adviser calculates a withholding ten times the tax owed.
October 6, 2026 4:32 AM
Bitcoin for a gift card: what paying with crypto means for your holding period
Paying for a gift card with Bitcoin is a sale for tax purposes. What counts as the disposal proceeds, when the twelve-month holding period bites, and the four records the tax office expects.
October 5, 2026 10:14 AM
Solana price 108.46 euros: a 2.4 percent gain in euros, a 2.5 percent loss in dollars: what to check now
Solana is quoted at 108.46 euros and $121.30 on Monday morning. That leaves a gain of 2.4 percent for 2026 in euros and a loss of 2.5 percent in dollars. The difference comes purely from the exchange rate, and in Germany it decides the holding period, the tax threshold and the figure that ends up on the tax return.
October 2, 2026 1:33 PM
Crypto tax before the cabinet on October 14: “Comments are only possible until October 6”
Germany's Federal Ministry of Finance sent the draft bill on crypto taxation to the associations on September 30, 2026, and the cabinet is to decide on October 14. For your holdings one date counts above all: December 31, 2026.
October 1, 2026 7:36 PM
Crypto tax and withholding at source from 2028: what to check now
The German Federal Ministry of Finance’s draft bill goes to cabinet on October 14, 2026. The underexposed part of it is the deduction of tax from 2028: which providers are to withhold the tax on investment income, why self-custody and foreign platforms stay exempt from it, and what you should document by December 31.
September 27, 2026 10:35 AM
Crypto Exchange Tax Report Wrong: How to Correct It Before the Tax Office Does
Missing acquisition costs, transfers booked as sales, holding periods restarted: your exchange's report is an aid and not proof. How to check it, how to correct it and which deadline is running.
September 26, 2026 1:19 AM

Germany’s Crypto Holding Period Is Wobbling: What to Check Before December 31
A CDU member of the Bundestag makes it plain: the coalition agreement does not guarantee that the one-year holding period for crypto assets will survive. What that means for purchases made before the planned cutoff date of December 31, 2026.
September 25, 2026 10:26 PM
Selling bitcoin privately: the tax in Germany and the records you need
A direct sale to a private individual falls under the same one-year rule as an exchange sale, but there is no tax report to go with it. This guide walks through the calculation, the 1,000 euro threshold and the records the tax office wants to see.
September 25, 2026 1:30 PM
NEAR Staking ETP Passes $100 Million: What to Check on Yield, Brokerage Account and Holding Period
The Bitwise NEAR staking ETP has crossed $100 million in assets under management while NEAR climbs to $4.99. Our own retrieval of the issuer's figures shows the price made the jump, not the inflows.
September 19, 2026 7:12 PM
Bitcoin Sold Without Austrian Tax Withheld: What to Do Next
Sold Bitcoin but no Austrian capital gains tax was withheld? That does not make the sale tax free. When investors have to declare the gain themselves at 27.5 percent.
September 19, 2026 7:26 AM
Offsetting Crypto Losses Against Share Gains: What Is Really Allowed in Germany
Crypto losses and share gains sit in separate loss buckets in Germany, and there is no offsetting between them. Where the line runs, why crypto derivatives are the exception, and how you can still use losses through carryback and carryforward.
September 18, 2026 10:13 AM
Bitcoin and the German Exit Tax: What Applies When You Move Abroad
Anyone emigrating with Bitcoin expects an exit tax on unrealised gains and finds nothing of the sort in the statute. Where the real risks sit is decided at four points: residence, the holding period, the legal form of your investment, and automatic reporting from 2026.
September 17, 2026 7:12 PM
Gifting Bitcoin to Children: Allowance, Holding Period and the Tax Office Report
Transferring Bitcoin to your child hands over your holding period and your entry price along with the coins. This guide sets out what really applies in Germany on the allowance, the reporting deadline, representation and custody.
September 9, 2026 4:22 PM
Crypto Tax in Germany: What Applies in 2026 and What Is Set to Change in 2027
In Germany, crypto gains are tax-free after twelve months; before that, your personal rate of up to 45 percent applies. What triggers tax, how the holding period works, what staking and losses mean, and where the 2027 reform stands after the cabinet date of 14 October.
September 9, 2026 4:13 PM
Bitcoin 29 Percent Below Last Year: Which Crypto Losses You Can Still Use Before the One-Year Holding Period Expires
Nine out of ten major crypto assets trade lower today than exactly twelve months ago, Bitcoin alone by 29.2 percent. We measured the price series ourselves and show why the purchase date alone decides the tax value of your loss.
September 9, 2026 1:15 AM
Germany's Crypto Tax: 160 Million Euros for a 555-Billion Budget
The German finance ministry's draft bill puts a figure on the crypto tax for the first time: 160 million euros from 2028. What that number means in the 2027 federal budget, how 11.4 billion became 160 million, and what investors can read from it.
September 8, 2026 1:19 AM
Germany's Crypto Holding Period: What Happens Now Signing for Petition 201716 Closed on September 15
Recap as of September 27, 2026: the signature period for German parliamentary petition 201716, which asks for the one-year crypto holding period to be preserved, closed on September 15, 2026. This article explains what ended that day, how the petitions committee proceeds and why no investor has to sell because of it.
August 31, 2026 10:30 PM
Taxing Crypto Lending: Your Personal Rate Instead of Withholding Tax, and the Right Federal Fiscal Court Case Number
According to the only tax court ruling so far, income from crypto lending falls under Section 22(3) of the German Income Tax Act and therefore under your personal tax rate. The appeal is pending at the Federal Fiscal Court under VIII R 22/25, not under the case number given in many professional articles.
August 27, 2026 10:32 AM
A Securities Account at the Crypto Exchange: Why Capital Gains Tax and Anlage KAP Are on You
On August 18, 2026 Kraken opened trading in more than 7,000 US stocks to customers in the European Economic Area, provided by a Cypriot investment firm. That puts the securities account abroad, and German capital gains tax, loss offsetting and the saver’s allowance now run through your own tax return.
August 26, 2026 10:25 PM
Selling Bitcoin at a Loss: Loss Offsetting in Austria
Sold Bitcoin at a loss? Austria allows the loss to be offset against certain investment income. When loss offsetting is possible and which limits apply.
August 22, 2026 4:47 PM
Offsetting Bitcoin Losses Against Stock Gains in Austria
Offset bitcoin losses against gains on shares? Austria allows it in principle, but only under certain conditions and usually via the tax return.
August 12, 2026 9:12 AM
Bitcoin Losses and Dividends in Austria: How the Tax Offset Works
Can a Bitcoin loss be offset against dividends? This is how loss offsetting works in Austria. It also shows when a tax return is needed for it.

July 31, 2026 10:59 AM
German Crypto Tax Return 2025: What You Should Know Now the July 31 Deadline Has Passed
Recap as of September 27, 2026: the deadline for the 2025 German tax return ended on July 31, 2026 at midnight. This article describes the situation on the day of the deadline: what crypto investors had to report and what happens if the deadline is missed.
More from CryptoTicker