The Cost Average Effect with Bitcoin: What Twelve Instalments Really Deliver
Twelve monthly instalments of 100 euros produced an average price of 66,472 euros and ran 33.6 percentage points ahead of the lump sum purchase on the same starting day. The calculation also shows when the savings plan is the worse route.

The cost average effect describes how, with constant instalments, you get more units for the same money when the price falls and fewer when it rises. What follows is an average price that lies below the average of the prices. How large that gap actually is goes unmentioned in most guides. So we calculated it ourselves: for twelve monthly instalments of 100 euros each in Bitcoin it comes to 3.67 percent, and against a lump sum purchase on the same starting day the savings plan portfolio is 33.6 percentage points ahead. This analysis was compiled by cryptoticker.io itself on September 19, 2026.
The figure alone does not yet say whether a savings plan is the right tool for you. The lead arose in a year in which the Bitcoin price gave up a good third from its high. In a rising market the result turns around. This article shows both sides using the same data.
What the cost average effect is and what it does not achieve
The term comes from the fund business and means a purely arithmetical consequence of fixed instalments. If you buy for 100 euros every month, then at a price of 50,000 euros you receive twice as many units as at 100,000 euros. Because the cheap months automatically carry more weight, your average price sinks below the arithmetic mean of the prices.
Two things the effect expressly does not achieve. It does not protect against losses: if the price falls lastingly, the value of your portfolio falls too, only more slowly than with a lump sum purchase at the starting price. And it does not generate a return out of nothing. What it delivers is a better entry price than the chance of a single buying day, as long as prices fluctuate.
Dollar cost averaging, DCA for short, is the English term for the same method and means the regular purchase of fixed amounts irrespective of the price level.
The calculation: what twelve instalments of 100 euros since October 2025 produced
How we calculated
The data basis is 366 daily closing prices for Bitcoin in euros from September 20, 2025 to September 19, 2026, retrieved on September 19, 2026 through the public price interface of CoinGecko. We simulated twelve instalments of 100 euros each, in each case on the first day of the month from October 1, 2025 to September 1, 2026, 1,200 euros in total. Valuation was at the price of September 19, 2026, which stood at 70,536.29 euros.
What this calculation does not contain: order fees, spreads between buying and selling price, the exact time of execution within the purchase day, and tax effects. Providers settle differently, and a savings plan is rarely executed at exactly the daily closing price. The values show the mechanics cleanly; they are not the statement of an actual portfolio.
What the figures show
The period was unusually eventful. The high was on October 7, 2025 at 107,019.40 euros, the low on July 1, 2026 at 51,473.91 euros. Between the two points lies a factor of 2.08. From the high to the cut-off date there is a decline of 34.1 percent.
| Purchase date | Price per bitcoin | Quantity bought | Average price after |
|---|---|---|---|
| October 1, 2025 | €97,215.68 | 0.00102864 BTC | €97,215.68 |
| November 1, 2025 | €94,506.90 | 0.00105812 BTC | €95,842.15 |
| December 1, 2025 | €77,843.13 | 0.00128463 BTC | €88,983.82 |
| January 1, 2026 | €74,525.49 | 0.00134182 BTC | €84,867.63 |
| February 1, 2026 | €66,363.23 | 0.00150686 BTC | €80,384.81 |
| March 1, 2026 | €56,991.79 | 0.00175464 BTC | €75,237.76 |
| April 1, 2026 | €58,760.27 | 0.00170183 BTC | €72,339.83 |
| May 1, 2026 | €65,065.83 | 0.00153690 BTC | €71,342.87 |
| June 1, 2026 | €63,253.57 | 0.00158094 BTC | €70,343.31 |
| July 1, 2026 | €51,473.91 | 0.00194273 BTC | €67,855.84 |
| August 1, 2026 | €54,453.33 | 0.00183643 BTC | €66,370.77 |
| September 1, 2026 | €67,612.11 | 0.00147903 BTC | €66,472.48 |
At the end there are 0.01805258 bitcoin in the portfolio, bought at an average price of 66,472.48 euros. By the cut-off date that has become 1,273.36 euros, a gain of 6.1 percent on the 1,200 euros paid in. Eleven of the twelve purchase days lay below the price of the first purchase day.
Why the average price lies below the average market price
The arithmetic mean of the twelve purchase prices is 69,005.44 euros. At 66,472.48 euros your actual average price lies 2,532.96 euros below it, so 3.67 percent cheaper. That is the cost average effect in its pure form, and it is nothing more than that.
Mathematically what lies behind it is the harmonic mean, the average that results when you buy fixed amounts instead of fixed quantities. With fluctuating prices it always lies below the arithmetic mean, and the gap grows with the range of fluctuation. At an asset that more than doubles and halves again within a year, it turns out markedly larger than at a broad equity index.
A sober conclusion follows from this: the 3.67 percent is the price advantage the method itself generates. Everything beyond that in our calculation stems from the price path and not from the savings plan.
 Bitcoin savings plans: providers and costs compared
The honest counter test: when the lump sum purchase wins
Had you invested the 1,200 euros in one go on October 1, 2025, it would have become 0.01234369 bitcoin. By the cut-off date that is 870.68 euros, a loss of 27.4 percent. The savings plan is therefore 402.68 euros or 33.6 percentage points ahead.
The worst conceivable entry would have been October 7, 2025, the high of the period. From 1,200 euros there would have been 790.92 euros, a loss of 34.1 percent. The best entry was on July 1, 2026 at the low: 1,644.40 euros, a gain of 37.0 percent. This value is the most important in the entire analysis, because it shows the reverse side. Whoever hits the low beats every savings plan by a clear margin.
Nobody hits it reliably. The savings plan, by contrast, buys with certainty in July 2026 and in August 2026 as well, the two cheapest months of the year, without you having to make a decision about it. That precisely is its contribution. In a year of rising prices the same mechanism would have led to nothing but more expensive follow-up purchases, and the lump sum at the start would have won. Which of the two situations comes along you do not know beforehand. How to weigh the two routes against each other we wrote up using the example of a specific price level in our analysis of savings plan or lump sum when buying more.
What the calculation conceals about fees and spreads
A savings plan buys twelve times a year, a lump sum purchase once. With percentage fees that hardly matters; with fixed minimum fees per order it very much does. A flat rate of one euro per execution costs you one percent of the purchase amount on a 100 euro instalment, so around a quarter of the entire cost average advantage of 3.67 percent.
On top of that comes the spread, the gap between the price at which a provider buys and the one at which it sells. With crypto savings plans it frequently lies between 0.5 and 1.5 percent and appears in no fee table, because it is contained in the price. Count it in before you compare providers. Which houses offer Bitcoin savings plans in Germany and how their cost models differ can be found in our comparison of providers for Bitcoin savings plans.
What routes exist in Germany and how to tell them apart
For regular Bitcoin purchases, essentially three routes come into question in Germany, and the difference rarely lies in the price. It lies in what you actually own at the end.
When buying through a trading venue authorised under MiCA you acquire the coins themselves; MiCA is the EU regulation for markets in crypto assets which since 2024 has set uniform authorisation duties for service providers. With an exchange traded certificate on Bitcoin, usually called an ETN, you hold a debt security of the issuer that tracks the price. With an offering that has no option to withdraw into a wallet of your own, you hold in the end merely a claim against the provider.
The difference only becomes visible when it matters, that is in an insolvency or a disruption at the provider. Before your first savings plan, therefore, check whether a withdrawal to an address of your own is possible and which minimum amounts apply to it. The selection of regulated trading venues is set out in the overview of crypto exchanges.
Holding period, FIFO and December 31, 2026: why every instalment has its own clock
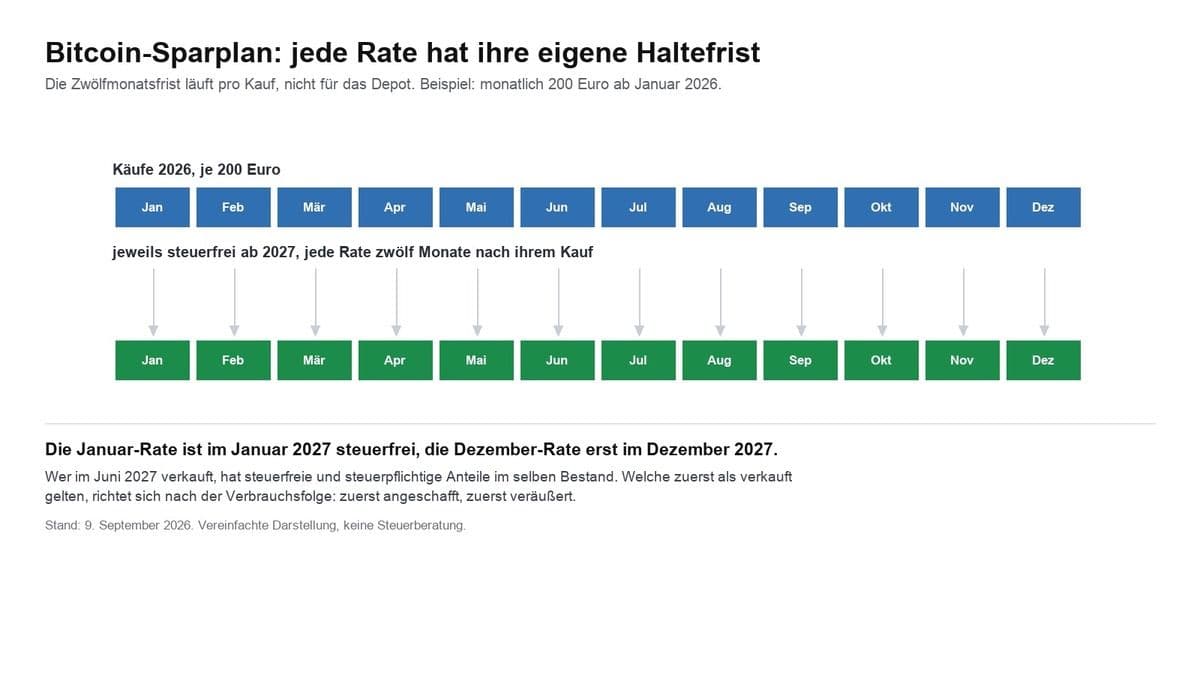
For tax purposes a savings plan is not a single event but a chain. Every instalment is an acquisition of its own with a date of its own. Under section 23 of the Income Tax Act, gains from private disposal transactions are tax free if more than a year lies between acquisition and sale; the wording can be found at Gesetze im Internet. With twelve instalments, then, twelve periods run in parallel.
If you sell part of the holding, in practice the FIFO method applies, first in, first out: what counts as sold is the holding bought first. In our simulation that would be the instalment of October 1, 2025 at 97,215.68 euros, the most expensive of the whole period. Anyone selling in September 2026 would thereby have realised a loss on paper and not the cheap July entry. The details on this are in our article on holding period and FIFO with a Bitcoin savings plan.
Added to that is a date currently under discussion. On September 8, 2026 the Federal Ministry of Finance submitted a draft bill for interdepartmental coordination which would treat crypto assets as income from capital assets and subject them to withholding tax. As the draft stands, only assets acquired after December 31, 2026 would be affected. A draft is not applicable law, and the further path through departmental coordination, cabinet and parliament is open. For a running savings plan it does mean, however, that instalments from January 2027 onwards may under certain circumstances be treated differently from those before. Keep the acquisition dates cleanly recorded.
How large the instalment should be and when you are better off pausing
A solid rule runs: the instalment has to remain bearable even if the price falls for twelve months. That very case occurred in our analysis, and the savings plan only worked because buying continued through the weak months. Anyone who had paused in March 2026 at just under 57,000 euros would have missed the three cheapest instalments of the year.
From this follows the most important practical pointer of this article. The instalment is not measured by what is possible in good months, but by the amount you can do without for twelve months at a stretch. You should pause a savings plan if you need the money for running costs or if debts at higher interest are outstanding. The price level, by contrast, is not a good reason, because pausing when prices fall inverts the mechanics exactly.
A common fallacy
Many investors raise the instalment after strong price rises and lower it after declines. That way you systematically buy more at high and less at low prices, and the cost average effect disappears. If you change the instalment, do it by reference to your income and not to the chart.
What speaks against the savings plan
Three objections are factually justified. First, the lump sum purchase regularly beats the savings plan in rising markets, because the entire capital is invested from the start; with equity indices this is the case in the majority of historical periods. Second, twelve purchases a year produce twelve acquisitions that you have to document, which noticeably increases the effort at tax return time. Third, the automation tempts you never to review the position.
The second point can be solved with tools that carry the acquisition dates and the FIFO order along automatically; we give an overview in the comparison of crypto tax tools. The first and third points remain a question of your investment horizon and your discipline.
Using the cost average effect: what to take away
- Count on 3.67 percent, not on a promise. That is the advantage twelve equal instalments generated against the average market price in our analysis. Everything beyond that came from the price path. Check first whether this advantage is not already eaten up by fees and spread at your provider, and compare the models in the savings plan comparison.
- Clarify before the first instalment what you are really buying. Coin, certificate or a mere claim against a provider are three different things, and the difference shows only when it matters. Check the authorisation and the withdrawal option of your trading venue using the overview of crypto exchanges.
- Document every instalment with date and price. With twelve instalments twelve one-year periods run, and on a sale FIFO reaches for the oldest. Should the draft bill of September 8, 2026 become law, the acquisition date will additionally decide the taxation. A tool from the tax tool comparison takes this bookkeeping off your hands.
(As of September 19, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Transparency note: This article was produced with the assistance of artificial intelligence and reviewed by our editorial team before publication. All figures and claims were checked against the primary sources linked in the text. The feature image was generated with AI.
Related articles
- Buying More Bitcoin at $77,000: Savings Plan or Lump Sum
- Fed Rate Decision on September 16: What a Hike Means for Your Bitcoin Savings Plan
- DCA Crypto: How to Survive Crypto Crashes with Dollar Cost Averaging and Invest for the Long Term
- Bitcoin Back Above $80,000: Buy More, Hold or Take Profits? What to Check Now
- Bitcoin Savings Plan and Tax: How the Holding Period, FIFO and the Exemption Limit Interact on Monthly Buys