


To file crypto taxes in the US, you report every sale, trade or spending of crypto on Form 8949 and Schedule D, report crypto income such as staking rewards as ordinary income, and answer the digital asset question on Form 1040. Gains on crypto held for more than one year are taxed at 0%, 15% or 20%; gains on crypto held one year or less are taxed like wages, at 10% to 37%. For tax year 2026, a single filer pays 0% on long-term gains as long as taxable income stays at or below $49,450, according to IRS Revenue Procedure 2025-32.
Crypto taxes at a glance
- Form 1040: every filer answers “Yes” or “No” to whether they received or disposed of a digital asset (IRS).
- Form 8949 and Schedule D: list each disposal with date, proceeds and cost basis.
- Form 1099-DA: brokers report digital asset sales beginning with transactions on or after 1 January 2025.
- Holding period: more than one year counts as long-term, one year or less as short-term.
- Losses: net capital losses lower other income by up to $3,000 a year ($1,500 if married filing separately); the rest carries forward (IRS Topic 409).
- Deadline: returns for tax year 2026 are due on 15 April 2027.
- UK readers: HMRC charges Capital Gains Tax above a £3,000 allowance, at 18% or 24%; see the UK section below.
What is Crypto Tax?
Cryptocurrencies like Bitcoin, Ethereum, and others are considered property for tax purposes in many jurisdictions, including the United States. This classification means that tax principles applicable to property transactions also apply to transactions involving cryptocurrencies. Thus, activities such as buying, selling, trading, or mining cryptocurrencies have tax implications.

When to Pay Crypto Tax?
1. Trading and Selling Cryptocurrencies
Any profit or gain realized from the trading or selling of cryptocurrencies is subject to capital gains tax. This includes exchanging one cryptocurrency for another or selling crypto for fiat currency.
2. Crypto Mining
Mining cryptocurrencies is considered a taxable event. The fair market value of the mined coins at the time of receipt should be declared as income.
3. Paying for Goods and Services
Using cryptocurrency to pay for goods or services is a taxable event, and you must report the capital gain or loss from the transaction.
4. Earning Cryptocurrencies
Earning cryptocurrencies through staking, airdrops, or as payment for services is considered income and is subject to income tax.
How to File Crypto Taxes
Step 1: Record Keeping
Keep detailed records of all your cryptocurrency transactions. This includes dates, values, gains, losses, and the purpose of each transaction.
Step 2: Determine Your Tax Liability
For each taxable event, calculate the gain or loss. This involves establishing the cost basis (the original value of the crypto when you acquired it) and subtracting it from the sale price or fair market value when you disposed of it.
Step 3: Report Your Transactions
Report your gains, losses, and income on your tax return. Different countries have varying forms and schedules for this, such as Form 8949 and Schedule D in the U.S.
Step 4: Pay Any Tax Due
After calculating your tax liability, ensure that you pay any taxes due by the tax filing deadline to avoid penalties and interest.

Utilizing Tax Software and Professionals
Tax Software
Several tax software tools are designed specifically for cryptocurrency transactions. These can automate much of the record-keeping and calculation process, integrating with exchanges and wallets to consolidate your transaction history.
Crypto Tax Forms: Which IRS Forms Do You Need?
For the IRS, crypto assets are digital assets: any digital representation of value recorded on a blockchain, a definition from the Infrastructure Investment and Jobs Act. The form you use to report digital asset transactions depends on the type of transaction, as the IRS digital assets page lists:
| Form | What it is for |
|---|---|
| Form 1040 | The digital asset question: “Yes” if you received, sold, exchanged or otherwise disposed of crypto |
| Form 8949 | Each sale, trade or spending of crypto held as a capital asset, with dates, proceeds and cost basis |
| Schedule D | The totals from Form 8949: net short-term and long-term gain or loss |
| Schedule 1 | Other income from forks, staking, mining or airdrops, if you are not in business |
| Schedule C | Mining or staking run as a business, with expenses |
| Form 1099-DA | Sent to you by brokers; shows gross proceeds of your digital asset sales from 2025 on |
| Form 709 | Gifts of digital assets above the annual exclusion |
Short-Term vs. Long-Term Capital Gains: Crypto Tax Rate for 2026
How long you held a coin decides the rate. Short-term gains are added to your other income and taxed at your ordinary rate. Long-term gains get their own, lower rates. The thresholds for tax year 2026 from Revenue Procedure 2025-32:
| Long-term rate | Single filers (taxable income) | Married filing jointly |
|---|---|---|
| 0% | up to $49,450 | up to $98,900 |
| 15% | up to $545,500 | up to $613,700 |
| 20% | above $545,500 | above $613,700 |
Worked example: selling with a $10,000 gain
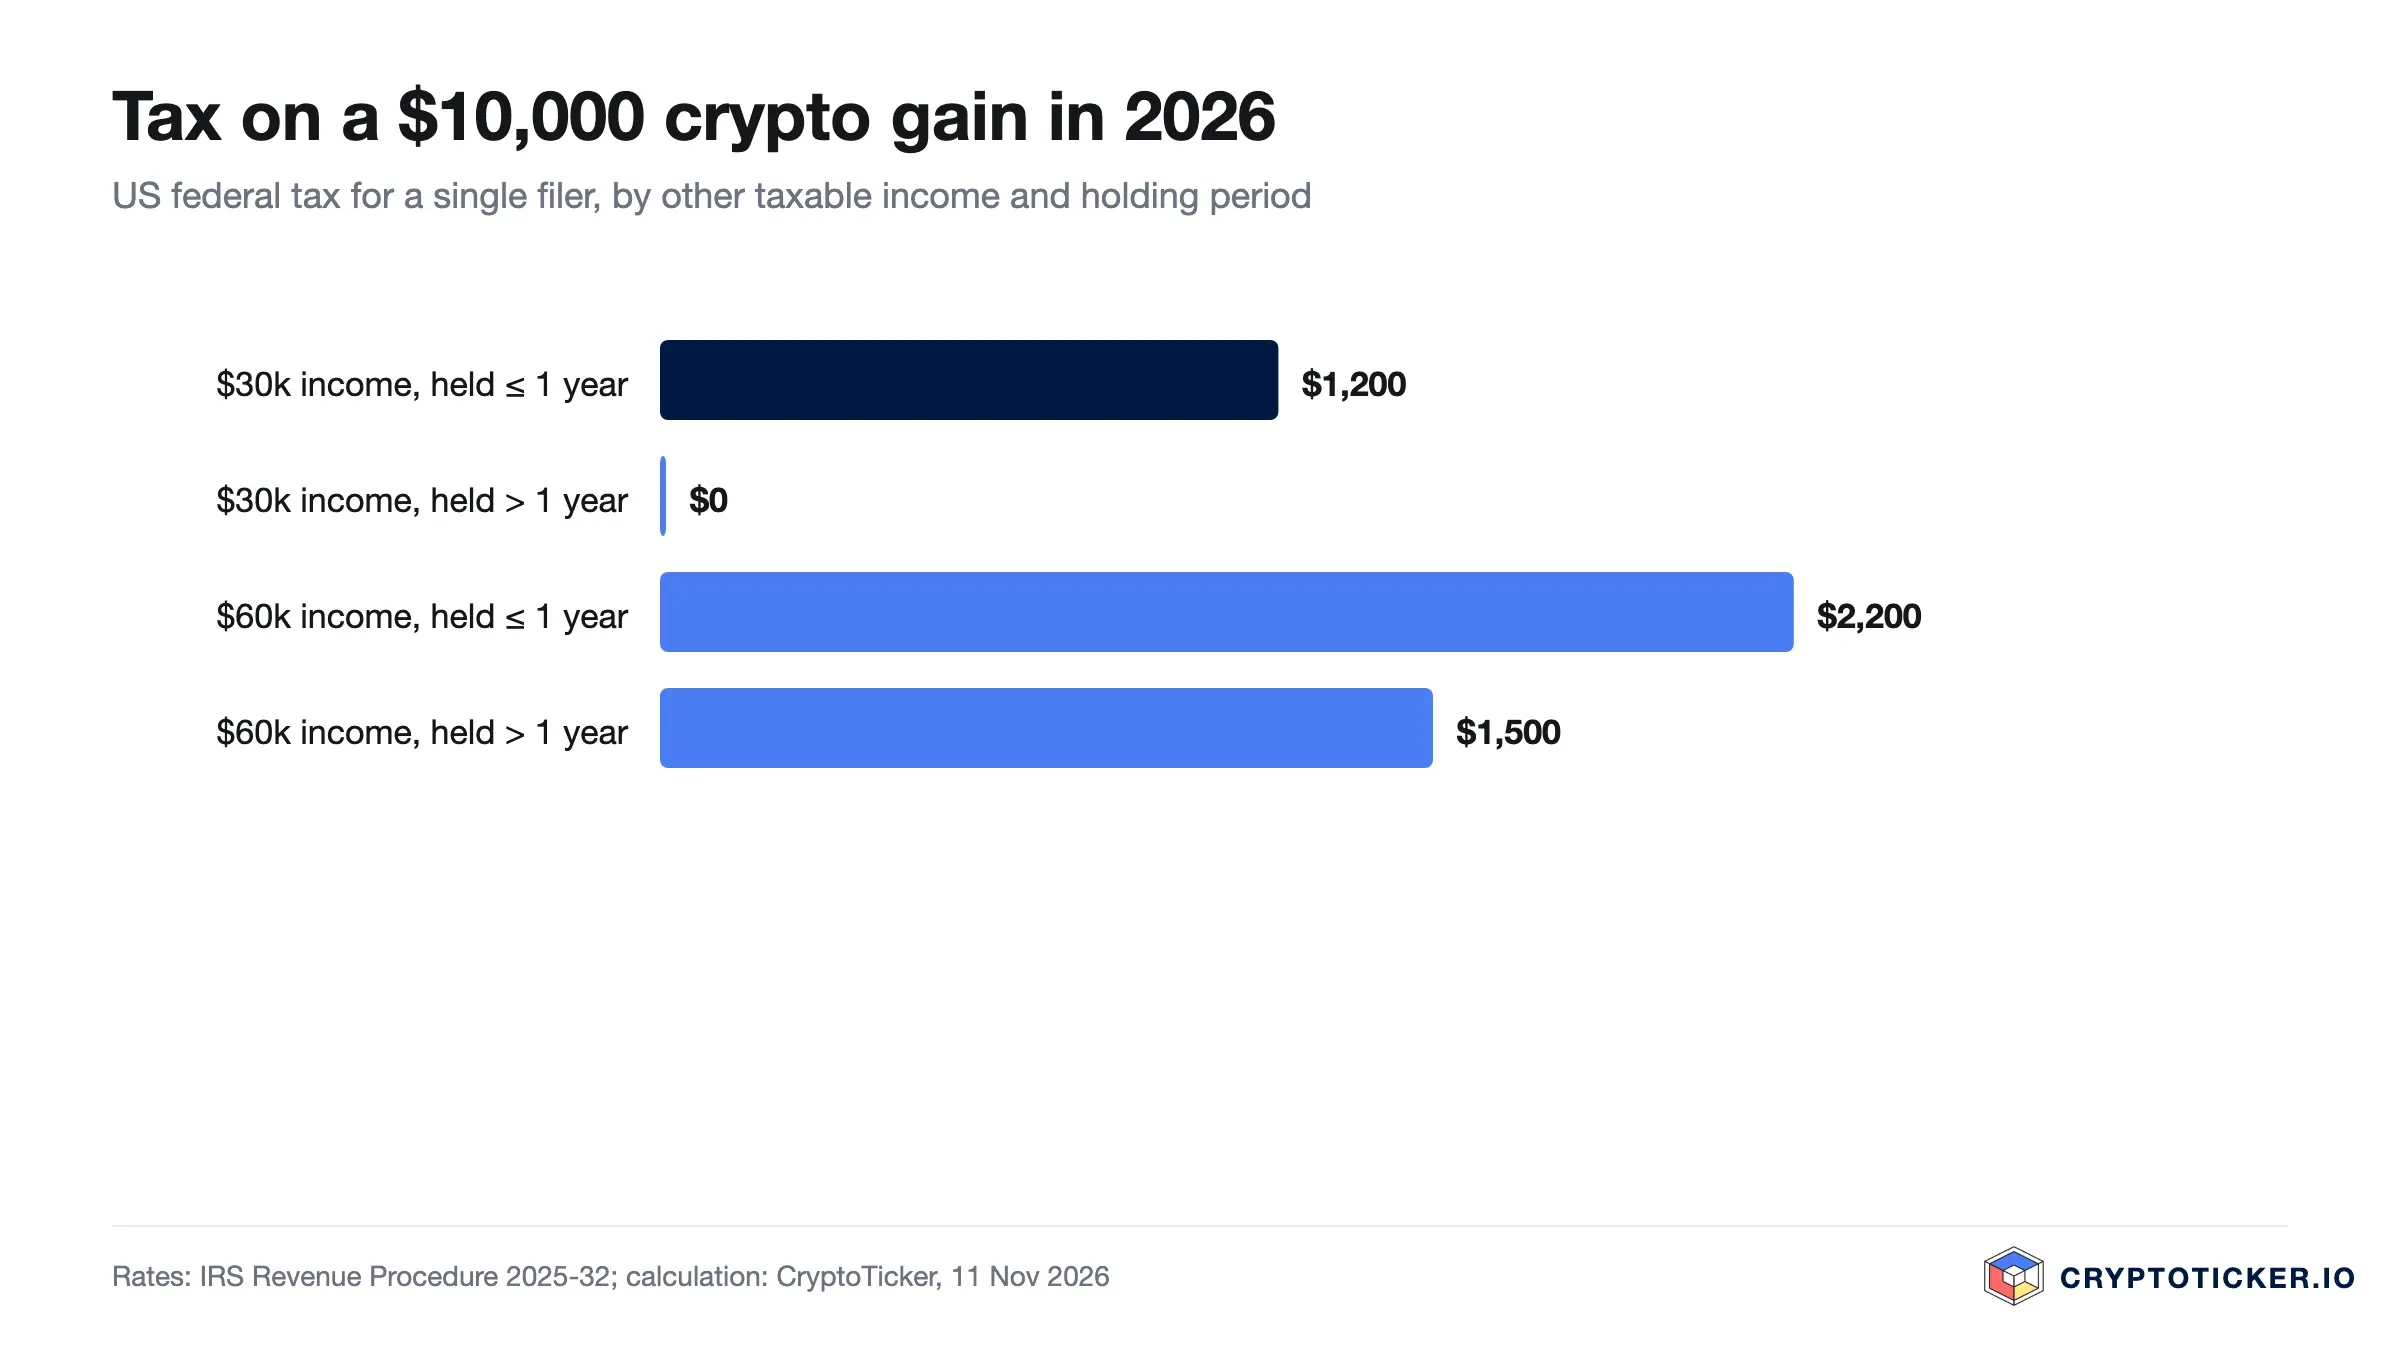
A single filer sells bitcoin with a $10,000 gain in 2026. We calculated the federal tax on the gain for two incomes, once after holding the coin for less than a year and once for more than a year:
| Other taxable income | Held one year or less | Held more than one year |
|---|---|---|
| $30,000 | $1,200 (12% bracket) | $0 (0% rate) |
| $60,000 | $2,200 (22% bracket) | $1,500 (15% rate) |
Waiting past the one-year mark saved $1,200 in the first case and $700 in the second. State taxes come on top in most states.

Professional Help
Consider consulting with a tax professional who is knowledgeable about cryptocurrency tax regulations. They can provide personalized advice and ensure that your tax filings are accurate and compliant.
Common Challenges and Tips
Decentralized Finance (DeFi)
Transactions involving DeFi platforms can complicate tax filings due to their complexity. It's important to have a clear understanding and records of all transactions, including swaps, liquidity pool contributions, and interest earnings.
 Click here to learn more about what DeFi is
Tax Loss Harvesting
This involves selling crypto assets at a loss to offset capital gains, which can be an effective strategy to minimize tax liability.
Staying Updated with Regulations
Tax laws and regulations concerning cryptocurrencies are evolving. Stay informed about the latest tax regulations in your jurisdiction.
Form 1099-DA: Digital Asset Proceeds From Broker Transactions
Since 1 January 2025, crypto brokers must report digital asset sales and exchanges of their customers on Form 1099-DA. You receive a copy, and the IRS receives one too. Compare it with your own records: the broker may not know what you paid for coins you moved in from another wallet, so you still need your own cost basis. Sales in self-custody wallets and on decentralized exchanges stay your own responsibility to report.
How Staking, Airdrops, NFTs and Mining Are Taxed
- Staking: rewards are ordinary income when you gain control over them (Revenue Ruling 2023-14). See our guide on how to stake crypto.
- Airdrops: tokens from an airdrop after a hard fork are ordinary income at their fair market value (Revenue Ruling 2019-24). More in our crypto airdrop guide.
- NFTs: the IRS may treat an NFT as a collectible, with up to 28% on long-term gains (Notice 2023-27). See our NFT guide.
- Mining: mined coins are income at their value on the day you receive them; a later sale adds a capital gain or loss.
Gifting Crypto and Charitable Contributions
Giving crypto as a gift is not a sale, so the giver usually owes no capital gains tax. In 2026, gifts of up to $19,000 per recipient stay below the annual exclusion (Revenue Procedure 2025-32); larger gifts are reported on Form 709. The recipient takes over the giver's cost basis. Donating crypto to a qualified charity can be deductible at its fair market value if you held it for more than a year; keep the charity's receipt.
Crypto Taxes in the UK: HMRC Rules
In the UK, crypto is taxed under Capital Gains Tax and Income Tax, as HMRC explains in its guidance on selling cryptoassets and its Cryptoassets Manual. You may owe Capital Gains Tax when you dispose of tokens: selling them, exchanging them for another cryptoasset, using them to pay for goods or services, or giving them away. The tax year runs from 6 April to 5 April.
| UK rule | What it means |
|---|---|
| Tax-free allowance | The first £3,000 of total gains per tax year are tax-free (gov.uk) |
| Rates | 18% on gains within the basic Income Tax band, 24% above it (gov.uk) |
| Cost basis | Tokens of the same type form a section 104 pool with an average cost; same-day and 30-day rules apply first (HMRC CRYPTO22200) |
| Staking | Usually miscellaneous income at the pound sterling value when received; Capital Gains Tax on a later sale (HMRC CRYPTO21200) |
| Airdrops | Not always income: tokens received without doing anything in return may be free of Income Tax (HMRC CRYPTO21250) |
| Reporting | Through Self Assessment; tax for 2025/26 must be paid by 31 January 2027 (gov.uk) |
The 30-day rule matters for loss harvesting: if you sell tokens and buy the same tokens back within 30 days, the sale is matched with the new purchase, not with your pool. Transaction fees count as allowable costs and reduce the gain. In other countries the rules differ; check with your national tax authority.
Common Crypto Tax Mistakes
- Forgetting crypto-to-crypto trades: swapping one coin for another is a disposal, even without cash.
- Missing cost basis: without purchase records, you may pay tax on the full sale price.
- Ignoring small payments: paying for goods with crypto is a taxable disposal too.
- Not using losses: realized losses offset gains and up to $3,000 of other income a year.
- Relying only on Form 1099-DA: it can miss wallet transfers, DeFi and the original cost basis.
Our assessment: the work is in the records, not in the forms. Export the history of every exchange and wallet once a quarter, and a tax tool or a professional can fill in Form 8949 in minutes.
Crypto Tax FAQ
Dennis Weidner
Dennis Weidner is managing director of Cryptoticker.io GmbH in Berlin and runs the editorial operation behind CryptoTicker, published since 2017 in German, English, French and Spanish. A founder and investor, he has worked with digital business models for more than twenty years. His writing focuses on the point where regulation meets what investors actually do: MiCA authorisation of trading venues, taxation and DAC8, self-custody and staking. He works from verifiable primary sources rather than price speculation: supervisory registers, vendor post-mortems, original specifications. His articles are analysis, not investment advice.