FinCEN drops the reporting duty for withdrawals to private wallets: what matters now for European investors
The US anti-money-laundering agency FinCEN withdrew two proposals on October 5, 2026 covering the reporting duty for self-custodied wallets and for mixers. In the EU the development runs in exactly the opposite direction: proof of ownership from 1,000 euros today, a ban on anonymous accounts from July 2027.


Which topics should we dive deeper into?
Select what genuinely interests you. Your picks feed directly into our editorial planning.
Crypto news that's actually worth your time.
Weekly. 60 seconds. Carefully curated by our editors: no hype, no promo flood, no spam.
The US financial regulator FinCEN closed two projects on October 5, 2026 that would have made transfers to self-custodied crypto wallets reportable. For you as an investor in Germany, nothing changes immediately. What happens when you withdraw to your own wallet is governed by European law, and European law is currently moving in the opposite direction.
FinCEN is the Financial Crimes Enforcement Network, the anti-money-laundering unit of the US Treasury. It prescribes which data banks and financial service providers must retain about payments and when they must file a report. Two of its proposals would have extended those duties explicitly to crypto transfers to wallets without a custodian for the first time. Both are now off the table.
What FinCEN withdrew on October 5, 2026
On Monday, October 5, 2026, the agency filed two withdrawal notices; publication in the Federal Register, the US official gazette, was scheduled for October 6. Two so-called NPRMs are affected, that is Notices of Proposed Rulemaking. An NPRM is the formal announcement of a planned rule on which anyone affected may comment before it takes effect.
The first project dates from December 23, 2020 and ran under the docket number 1506-AB47. The second was published on October 23, 2023 and carried the number 1506-AB64. The older one had thus sat unresolved for almost six years, the newer one for three. Neither was ever in force; they hung in the state in which an agency has announced a rule but not adopted it.
The $3,000 threshold and the report from $10,000
The December 2020 proposal would have required banks and payment service providers to keep records on crypto transactions involving a self-custodied wallet from $3,000 upwards, including details of the counterparty. From $10,000 a report to FinCEN would have become due. A self-custodied wallet, an unhosted wallet in the agency's English, is a wallet whose private key nobody but you holds; there is no company there that could provide information.
That was precisely where the dispute lay. Anyone sending money to an address with no service provider behind it can say about the recipient only what that recipient states themselves. The criticism of the proposal therefore came down to the duty being either impossible to fulfil or an invitation to guess. In 2021 the industry filed several thousand comments within an unusually short window.
Why the 2023 mixing special measure fell
The second project targeted mixers. A mixer is a service that pools payments from many users and pays them out in a new distribution, so that the trail between deposit and withdrawal can no longer be drawn unambiguously in the blockchain. FinCEN wanted to designate international crypto mixing under section 311 of the USA Patriot Act as a class of transactions of primary money-laundering concern. The consequence would have been a duty to report wallet addresses, transaction hashes and IP addresses.
That it comes to nothing is justified by the agency, according to Decrypt, by the reporting burden and by the objection of many commenters that the broad definition could deter lawful use. FinCEN stated verbatim that it would take no further action on this NPRM. Both withdrawals refer to the White House digital asset report of July 2025 and its sentence that lawful users of digital assets should be able to transact privately on a public blockchain.
The legal basis remains in place
A withdrawal is not a ban on the rule but the end of a single proceeding. Peter Van Valkenburgh of the advocacy group Coin Center said on that point that the underlying statutory authority to create new, similarly bad rules remains. That is the sober reading: what was withdrawn is the proposal, not the power to write a new one.
The same agency tightens the screws on the A7 network the same day
That FinCEN is pulling back across the board cannot be inferred from the day. On October 5, 2026 the same agency published a new finding together with a proposed rule in the Federal Register under the number 1506-AB77. It is directed at companies outside the US controlled by the so-called A7 network, a service for sanctions evasion and money laundering with links to Russia. The legal basis is section 9714(a) of the Combating Russian Money Laundering Act.
What is proposed is a prohibition on certain transmittals of funds by covered financial institutions. The comment period ends on November 4, 2026. The pattern is therefore recognisable: the agency is abandoning blanket capture of private transfers and working instead with targeted prohibitions against named networks.
 Hardware wallets compared
Proof of ownership from 1,000 euros: how far the EU transfer-of-funds regulation reaches
In the European Union, Regulation (EU) 2023/1113, the transfer-of-funds regulation for crypto assets, has applied since the end of 2024. Its Article 14 requires that, for a transfer to a self-hosted address above 1,000 euros, the originator's crypto service provider take appropriate measures to establish whether that address is owned or controlled by the originator. A self-hosted address is the same thing FinCEN calls an unhosted wallet: an address with no service provider behind it.
In practice that means your exchange wants to see proof above this threshold that the destination address belongs to you. What that proof looks like we set out in a separate assessment of which providers demand which evidence from 1,000 euros. Below the threshold it stays with the details that are collected anyway. Anyone intending to self-custody permanently cannot avoid the question of which device the keys sit on; our hardware wallet comparison sorts the devices by price, handling and supported networks.
So the EU demands precisely what the US is now dropping: an attribution of transfers to wallets without a custodian. The difference is the direction of access. The American rule would have produced a report to the agency. The European one produces a duty of verification at the service provider, the result of which is documented there.
The anti-money-laundering regulation from July 10, 2027 and the end of anonymous accounts
The second building block is not yet in force. Regulation (EU) 2024/1624, the EU anti-money-laundering regulation, applies from July 10, 2027. Its Article 79 prohibits credit institutions, financial institutions and crypto service providers from keeping anonymous accounts. At the same time it prohibits dealing in anonymity-enhancing coins, that is crypto assets whose protocol systematically conceals sender, recipient or amount. Monero is the best-known case.
For regulated exchanges in the EU that means taking such coins out of their offering. What exactly this prohibition captures and what holders can do until then we treated separately in an assessment of the privacy coin ban from 2027. What stands for today's occasion is this: while surveillance of private transfers is being rolled back in Washington, a deadline is running in the EU after which a part of private transfers will not be possible at all through regulated providers.
Which provider sits under which supervision is therefore no longer a formality but decides which coins you will still be able to trade there in two years. Our overview of regulated crypto exchanges lists who holds an authorisation under the European crypto market regulation MiCA and in which member state it was granted.
What happens on a withdrawal to your own wallet in Germany
The procedure differs by provider, but the components are the same everywhere. You enter the destination address, and above the 1,000-euro threshold the provider asks for proof that it belongs to you. Common forms are a signed message from the wallet, a screenshot of the address in the wallet software, or a small test transfer. Some providers additionally work with an allowlist on which a new address only becomes usable after a waiting period.
The American withdrawal changes nothing about that, for a simple reason: the duty falls on your service provider, and your service provider is as a rule based in the EU or serves you under European supervision. A provider licensed in Germany follows the transfer-of-funds regulation, not whatever FinCEN plans or drops. Anyone trading with a provider outside the EU leaves that framework; then what applies there applies, and the way back to a German bank account runs through the European rules again.
 Regulated crypto exchanges with MiCA authorisation
These five details to check before your next withdrawal
Before you pull holdings off an exchange and onto your own wallet, five points are worth a look, as they cause most of the delays in practice.
- The amount threshold. If the withdrawal is above 1,000 euros, the duty of proof under Article 14 applies. Anyone staying just below it to avoid that runs into the opposite: a series of conspicuously small transfers is a pattern any money-laundering desk examines.
- The network. The same coin often exists on several networks. A withdrawal on the wrong network does not arrive and in many cases cannot be recovered.
- The form of the proof. If the provider demands a signed message, your wallet has to be able to do it. Not every app offers the function, and with a hardware wallet it sometimes sits in the companion software rather than in the device.
- The waiting period on the allowlist. If a newly entered address only becomes usable after hours, a withdrawal is not something for the evening before a deadline.
- The records. Acquisition date, acquisition cost and the transaction number belong saved before you leave the account. Anyone requesting them from the exchange later gets them in the best case; in the worst, the provider is gone.
In tax terms the withdrawal changes nothing in Germany
A transfer between two of your own wallets is not a sale and in itself produces no taxable gain. What it does produce is documentation work: after the move, the holdings sit where no service provider draws up an annual statement any more. The duty to be able to evidence the acquisition date and acquisition cost stays with you. Tools that read addresses along permanently and build a statement from that we set side by side in the crypto tax tool comparison.
That a reorganisation of crypto taxation is being negotiated in Berlin at the same time is a separate matter and has nothing to do with the American reporting duties. For the question of where your coins sit it is nonetheless not immaterial: the longer a holding sits with you yourself, the more important it becomes that the origin of every position stays traceable.
Self-custody: What to take away
The news from Washington is a relief for American financial service providers and a signal to everyone who treats self-custody as a case for suspicion. A change in your situation in Germany it is not. Three steps follow from it.
- Settle where your keys are to sit. Anyone wanting to take holdings off an exchange permanently decides on the device first and only then on the timing. Our hardware wallet comparison names the differences that matter in doing so.
- Check your provider's authorisation. From July 2027 it decides which coins remain tradable there. The overview of regulated crypto exchanges shows who holds a MiCA authorisation.
- Secure the records before you move. Acquisition data and transaction numbers are harder to obtain after leaving the account than before; a tax tool keeps them together permanently.
(As of October 6, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
Sources for further reading: the withdrawn proposal of December 2020 in the Federal Register and the mixing special measure of October 2023 in the same place.
Frequently asked questions about self-custody
Transparency note: This article was produced with the assistance of artificial intelligence and reviewed by our editorial team before publication. All figures and claims were checked against the primary sources linked in the text. The feature image was generated with AI.
Related articles
- Crypto Withdrawals to Your Own Wallet: Why Exchanges Demand Proof of Address Ownership Above €1,000
- Crypto Withdrawal to Your Own Wallet: Ten Providers Checked, Three Will Not Let Your Coins Out
- Wallet App Without BaFin Authorisation: When Holding Crypto-Assets Requires a Licence
- Chainlink Jumps Above $12: What LINK Holders Should Check Now
- Customers Pull $463 Million From Bitget: The Consequences for Reserves and Custody
Which topics should we dive deeper into?
Select what genuinely interests you. Your picks feed directly into our editorial planning.
Crypto news that's actually worth your time.
Weekly. 60 seconds. Carefully curated by our editors: no hype, no promo flood, no spam.

June 30, 2026 11:20 PM
How to Switch from Binance to a MiCA Regulated Crypto Exchange
Binance is winding down EU services after missing the MiCA deadline. Here's why it's happening and how to move your funds to a regulated platform safely.

September 4, 2026 4:39 AM
Source of Funds at a Crypto Exchange: Why a Deposit Can Freeze Your Account for 15 Days
OKX chief Star Xu described on September 2 what an unusual deposit sets off: reviews of 15 days and longer, during which balances and account functions can be restricted. What that means for investors in Germany, and which documents you should keep to hand.
July 10, 2026 10:30 AM
Binance Reveals Where Its EU Users Went After MiCA
Binance just revealed where most departing EU users moved their crypto after MiCA — and the answer is raising hard questions about the new rulebook.
September 17, 2026 4:14 PM
D'CENT App Wallet: How to Tell If Your Recovery Phrase Has to Move Now
Manufacturer IoTrust reports suspicious asset transfers in the D'CENT app wallet and asks users to move their holdings. One question decides the matter: has your recovery phrase ever been entered into the app?
August 15, 2026 9:31 PM
Crypto Exchange Shutting Down: What to Do Before the Deadline Passes
Binance, BitMart, Luno and Revolut have ended or cut back their European business within seven weeks. This guide shows which deadline expires first, how a forced sale is treated for tax, and what to secure before the account closes.
September 29, 2026 10:14 AM
387.5 million dollars at Bitget: the attack ran through a bought-in security product, what to watch now
Bitget has disclosed how the attackers reached its withdrawal systems on September 24: through a previously unknown flaw in a security product it had bought in. The second stage of the withdrawal schedule opens today at 08:00 UTC, and for the balance you keep on any exchange the case changes the arithmetic.
August 30, 2026 10:38 PM
Crypto Cards: Where Your Card Balance Really Sits and What the August 28 Solana Exploit Reveals About It
An attack on a card balance contract on Solana took the loaded balance from 1,685 users while their wallets stayed untouched. The case shows why it matters whether your crypto card holds funds as e-money at a licensed institution or in a smart contract.
August 19, 2026 10:24 AM
Privacy Coins and EU Anti-Money-Laundering Law: An Assessment of the Ban From July 2027
Article 79 of the EU anti-money-laundering regulation bars crypto service providers from keeping accounts that obscure transactions, and it names anonymity-enhancing cryptocurrencies explicitly. This assessment separates the documented wording, including the 10 July 2027 application date, from what follows for individual coins.
September 27, 2026 4:32 AM
Hester Peirce Leaves the SEC: What Now Applies to Your Custody in Germany
The most crypto-friendly voice at the US securities regulator goes on October 2, 2026, and the commission shrinks to two members. For investors in Germany it is still the European rulebook that decides, and there a deadline falls in July 2027.
September 25, 2026 4:11 AM
Bitget Hack of $351 Million: What to Check at Your Crypto Exchange Now
Bitget reports unauthorised outflows of around $351.6 million and has suspended withdrawals. For existing customers in Europe, that closes the one route MiCA had left them.
September 7, 2026 7:26 PM
Stolen Keys Beat Code Flaws: Why the Private Key Is the Way In for 2026 Crypto Hacks
Compromised private keys overtook smart contract code flaws as the most common attack route for the first time in 2026. What sits behind the shift, and how to check your own setup for its single point of failure.
August 11, 2026 1:32 PM
How to Store a Seed Phrase Safely: What Steel, a Passphrase and Multisig Do for Your Wallet Backup
The Coldcard case pushed the manufacturer question to the front, while barely touching on where the backup is kept. This guide places paper, steel, the passphrase and splitting methods against the BIP-39 and SLIP-0039 standards.
August 20, 2026 10:24 PM
MiCA Review: What the European Commission Could Change About the EU Crypto Rules
The European Commission has reopened MiCA for review after barely two years and is asking 86 questions covering the stablecoin interest ban, staking, lending and DeFi. Brussels is taking responses until September 30, 2026.

June 17, 2026 7:21 PM
Binance EU Access at Risk: What MiCA Could Mean for BNB and Crypto Users
Binance is facing one of its biggest regulatory tests in Europe as the MiCA deadline approaches. Could this put BNB and EU crypto users under pressure?
July 2, 2026 8:59 PM
Binance Is Out of the EU: How to Move to a MiCA-Regulated Exchange
Binance has left the EU market. Which exchanges hold a MiCA licence, how to verify an authorisation is real, and how to move your holdings across step by step.
September 19, 2026 4:11 PM
MiCA Consultation Closes September 30: What to Check and Submit Before Then
The European Commission is reviewing the MiCA crypto regulation and will accept submissions until September 30, 2026 at 23:59 CEST. Staking, DeFi, lending, stablecoins and custody are all under examination, and you can take part without a lawyer.
October 2, 2026 4:32 AM
NEAR Intents halts withdrawals after a $3.8 million exploit: here are the reasons
NEAR Intents confirms an exploit of more than $3.8 million and holds deposits and withdrawals on eleven networks. Reimbursement is promised, a date for it is not.
September 30, 2026 4:15 PM
Zcash today: 2,746 ZEC from the Bitget hack vanish into the Ironwood pool
Wallets from the Bitget break-in pushed 2,746 ZEC into Zcash's Ironwood pool on Wednesday morning, roughly $3.9 million. What the shielding means for tracing, and what applies to your exchange account from July 2027.
September 26, 2026 4:14 PM
Bitget Withdrawals Resume on September 28: What to Check on a Residual Balance Now
Bitget is releasing the withdrawals frozen after the September 24 incident in four stages from September 28. For a residual balance held from Germany that is a deadline, not a reason to wait.
September 4, 2026 10:15 PM
Trezor Data Breach: Am I Affected and What Should I Do Now?
Trezor widened the ShipMonk data breach on September 4, 2026: around 67,000 further people affected, just over 80,000 in total, from orders placed between November 2019 and August 2021. How to check in two minutes whether you are among them, and what an exposed home address means for self-custody.
September 4, 2026 10:17 AM
Cypher Shutdown on September 6: What Users Should Know Now the Withdrawal Deadline Has Passed
Recap as of September 27, 2026: Cypher had announced it would take its app, dApp and withdrawal window offline on September 6, 2026 and end the token protocol. This article describes the situation before the deadline, how the payout worked and what our own measurement showed at the time about what was left of the CYPR token.
September 16, 2026 7:39 PM
Deutsche Bank to Custody Bitcoin and Ether: Why Retail Clients Are Missing and What to Check in Your Own Custody
Deutsche Bank will custody Bitcoin, Ether and three stablecoins, but addresses corporates and institutions only. What the launch under supervisory reservation means, and the four questions you should put to any custody arrangement.
August 6, 2026 3:05 PM
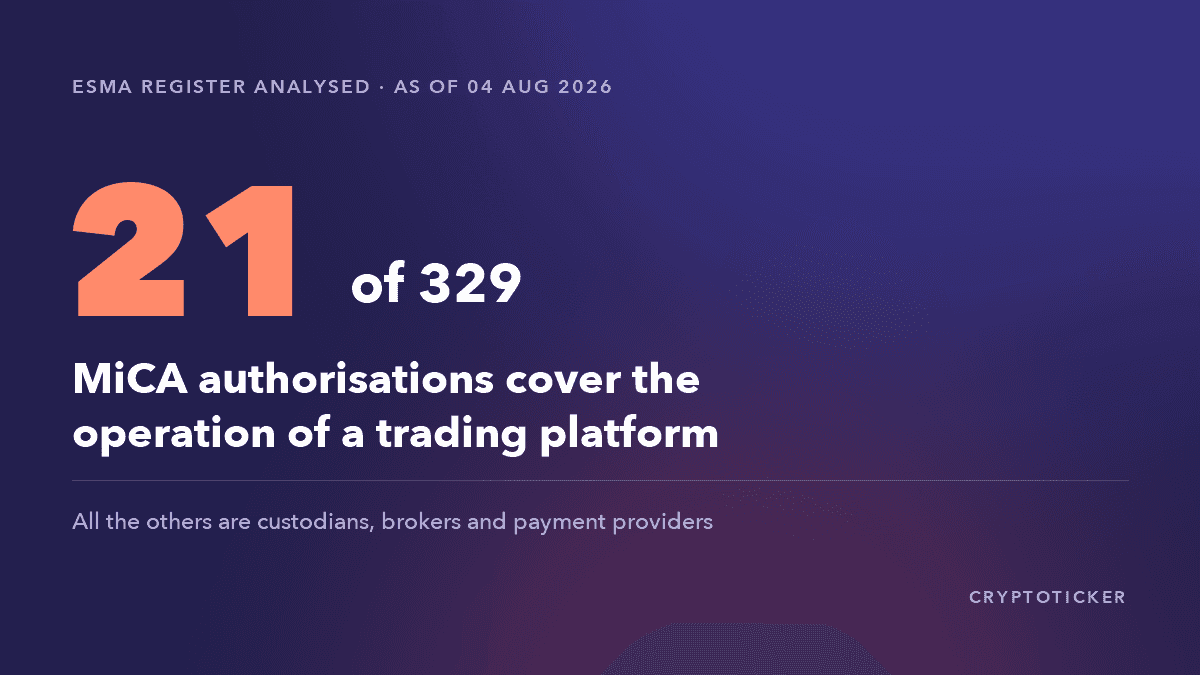
MiCA Register 2026: Only 21 of 329 Licences Are Real Exchanges
ESMA publishes the register of MiCA-authorised providers as an open file. We worked through all of it — and the result is not what the phrase “licensed crypto exchange” suggests.
September 23, 2026 4:12 AM
How to Set Up a Crypto Wallet: Securing Your Coins in Seven Steps
Your own crypto wallet is set up in twenty minutes, yet a single step decides everything that follows. This guide takes you through wallet type, recovery words and the test amount, and sets out what BaFin and the tax office expect.
August 24, 2026 1:22 PM
Phantom Wallet Ends Sui and Monad Support: What to Do Before the Deadlines
Phantom Wallet removes Monad from its app on August 26 and Sui on September 24. The balances are not lost, but only one of the two ways out leaves your tax position untouched.
July 7, 2025 8:12 PM

BIG Crypto News: EU Approves 14 Stablecoin Issuers Under MiCA
Six months into the MiCA rollout, Europe’s crypto regulatory landscape is taking shape. From authorized stablecoin issuers to licensed crypto service providers, here’s the full July 2025 update.
September 25, 2026 4:20 AM
Crypto as a Down Payment for a German Mortgage: What Banks Require
Since April 2023 a house in Germany can no longer be paid for in Bitcoin; section 16a of the Money Laundering Act bans it outright. Your crypto holdings still work as a down payment, provided you take the route through the euro and prove the origin without gaps.
More from CryptoTicker